

Energy Vault Holdings, Inc.
AI Upside, Storage Strength, and Mispricing
Published: May 7, 2026
Author: FRC Analysts
Disclosure: Energy Vault Holdings, Inc. has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions.
Company Details
Sector – Utilities
Industry – Utilities-Renewable
Trading Information
Trading information – NRGV : NASDAQ
Report Highlights
- Accelerating Pipeline & Global Buildout: Backlog rose to $1.35B (Q4: $1.30B), with ~80% from proprietary projects, and the remainder from third-party deployments. Expanded portfolio with 175 MW in Texas, and 350 MW in Japan (2027–2028 completion). Total managed assets reached 1,066 MW (+461% YoY), including 66 MW operational, with remainder coming online over two-three years. The company continues to expand its asset base ahead of our expectations, supporting an upward revision to our long-term revenue outlook. However, with most projects still pre-construction, execution remains key to realizing the full upside.
- Strategic Entry into AI Infrastructure: NRGV is entering digital infrastructure with a 100 MW AI data center integrating generation and storage, alongside its core storage portfolio. We view this expansion into a high-growth adjacent sector as strategically important, supported by rising AI-driven power demand, stronger margins, and premium valuation multiples relative to traditional energy storage companies.
- Stronger Energy Storage Tailwinds: Geopolitical tensions, including in the Middle East, are reinforcing demand for diversified and resilient energy systems, boosting energy storage adoption. The market outlook remains strong, supported by rising electricity demand, grid reliability needs, and growth from AI data centers and renewable integration.
- Revenue Beat, Modest EPS Miss: Q1 revenue, primarily driven by third-party deployments, increased 156% YoY, beating our estimate by 47%. Adjusted EPS declined YoY, from ($0.08) to ($0.12), below our estimate of ($0.10). Quarterly revenue remains difficult to forecast due to variability in project completion timing. Management reaffirmed 2026 revenue guidance of $225–$300M (~30% YoY), and we maintain our $248M forecast.
- Significant Valuation Discount: NRGV trades at 13x forward EBITDA vs the sector average of 17x, a 23% discount.
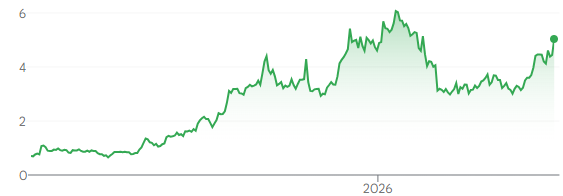
Price and Volume (1-year)
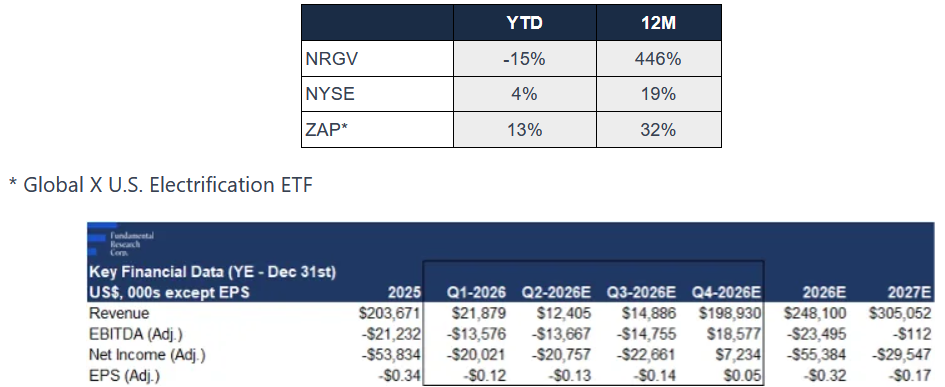
* Energy Vault Holdings has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions. All figures in US$ unless otherwise specified.
In Q1-2026, the company expanded its portfolio with a 175 MW project in Texas, and a 350 MW portfolio in Japan
Both projects are designed to support grid stability, and renewable integration, with completion expected in 2027–2028
NRGV now manages 1,066 MW of assets, up 461% YoY, with 66 MW operational, and the remainder expected online within two to three years
Asset Vault Portfolio
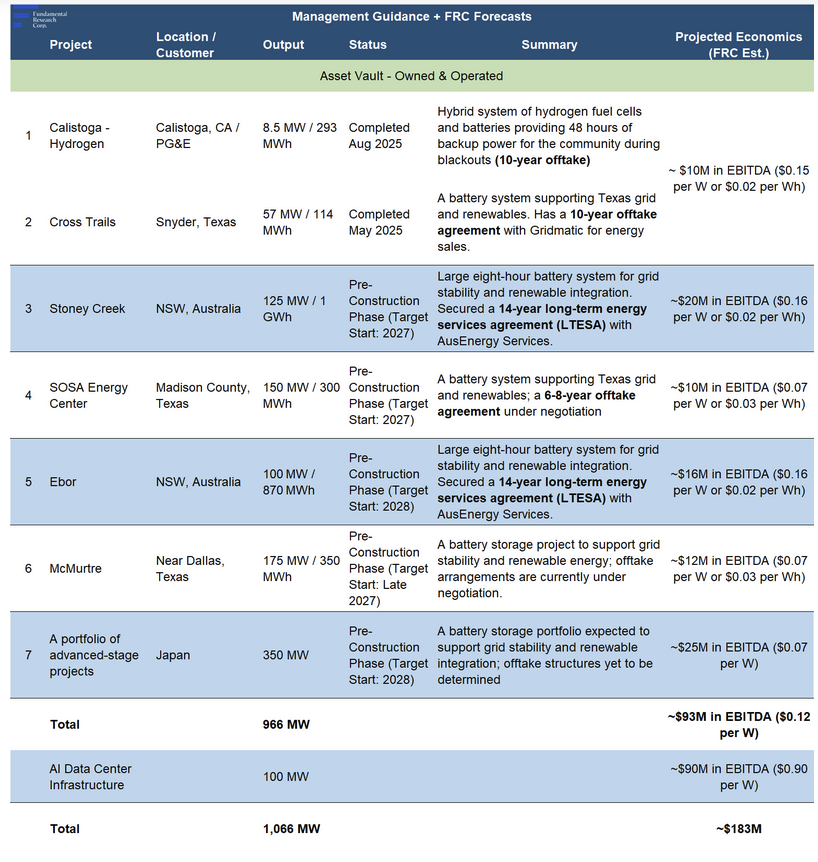
* Project economics depend on storage duration; duration refers to how long a system can supply power; longer-duration projects earn more EBITDA per MW (e.g., Sosa: two-hour → $0.07/W, Stoney Creek: eight-hour → $0.16/W)
* CAPEX to build a system is ~$0.30/Wh in the U.S., and ~$0.20/Wh outside the U.S.
Source: Company / FRC
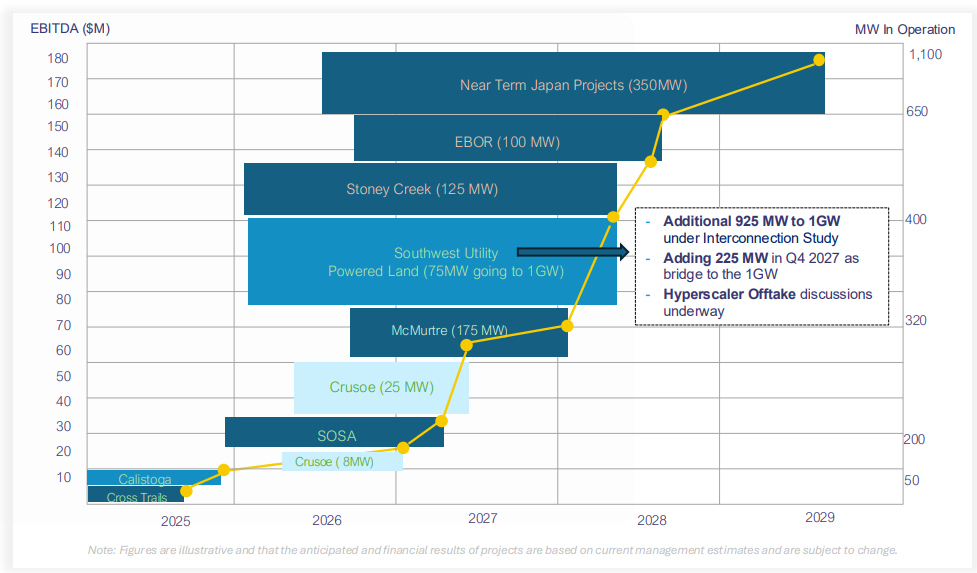
Management projects ~$180M in annual EBITDA at full operation, with a long-term target of $1.8B+ from a ~4 GW portfolio by 2030
Projected Timelines
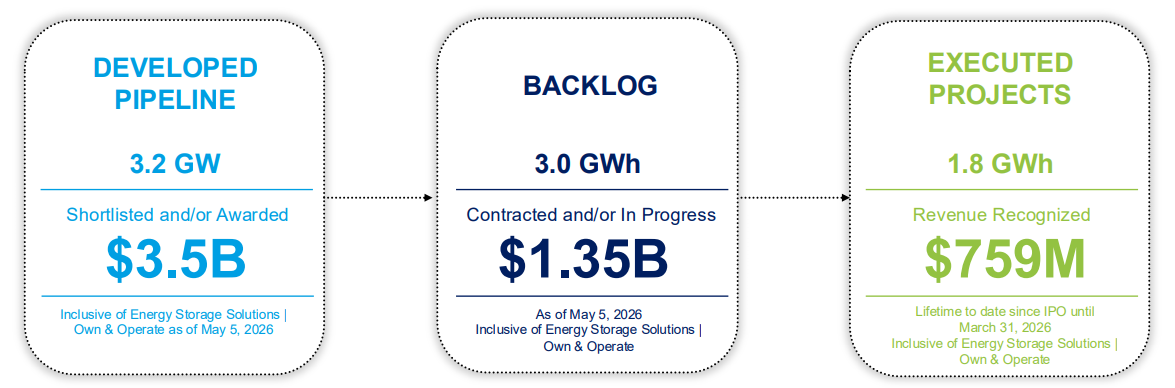
By the end of Q1-2026, NRGV had $1.35B in contracted backlog (Q4: $1.30B), and a $3.50B pipeline (Q4: $3.00B), with ~80% from its own projects, and the remainder from third-party deployments
Project Pipeline
Expanding into Digital Infrastructure
The current portfolio includes a new 100 MW AI data center infrastructure project. While the rest of the portfolio consists of energy storage assets, this project integrates energy generation , and storage to power AI data centers.
Higher-margin expansion beyond core energy storage assets
This marks the company’s entry into the digital infrastructure space , which includes the energy and computing backbone for AI, cloud computing, and data centers. It is one of the fastest-growing , and most in-demand infrastructure segments, driven by accelerating AI adoption, rising cloud workloads, and increasing power intensity requirements.
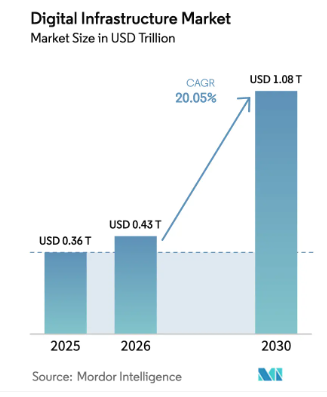
Forecast to grow at a CAGR of 21% from 20226 to 2030
Given its broader scope, such projects carry significantly higher margins (~$1/W in EBITDA vs ~$0.10/W for standalone storage). The company is increasingly focused on scaling this segment alongside its storage business. We believe this new business line is strategically important, driven by rising demand for AI-driven digital infrastructure, materially higher margins, and stronger market sentiment, with higher EBITDA multiples than traditional storage assets.
To view the complete report, click on the button above.
The opinions expressed in this report are the true opinions of the analyst(s) about any companies and industries mentioned. Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The companies listed above are covered by FRC under an issuer-paid model, where fees have been paid to FRC to commission this report and research coverage. This creates a potential conflict of interest which readers should consider. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time. To subscribe for real-time access to research, visit https://www.researchfrc.com/plans for subscription options. This report contains “forward looking” statements. Forward-looking statements regarding the Company, industry, and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company’s products/services in the marketplace; acceptance in the marketplace of the Company’s new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company’s periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated, and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
