

Market Intel Weekly
Fed Fears Weigh on Markets; Spotlight on a New Potash Opportunity
Published: June 9, 2026
Author: FRC Analysts
Disclosure: Articles and research coverage are paid for and commissioned by issuers, except for those listed under the “FRC Fair Value Model Picks” section. See the bottom for other important disclosures, and issuer-specific information.
*Disseminated on behalf of Giga Metals Corporation, DLP Resources, Enterprise Group, Builders Capital Mortgage, Olympia Financial Group, Gensource Potash, Cupani Metals, Focus Graphite, Blue Star Helium, Eskay Mining, Denarius Metals, Nimy Resources, and Nine Mile Metals.
* All figures are in C$ unless otherwise noted, except for commodity prices, which are in US$.
Equity markets pulled back last week as stronger than expected U.S. jobs data increased expectations that the Fed may raise interest rates. Basic materials significantly underperformed, weighed down by weaker commodity prices, while technology stocks lagged as investors rotated away from higher-risk growth names.
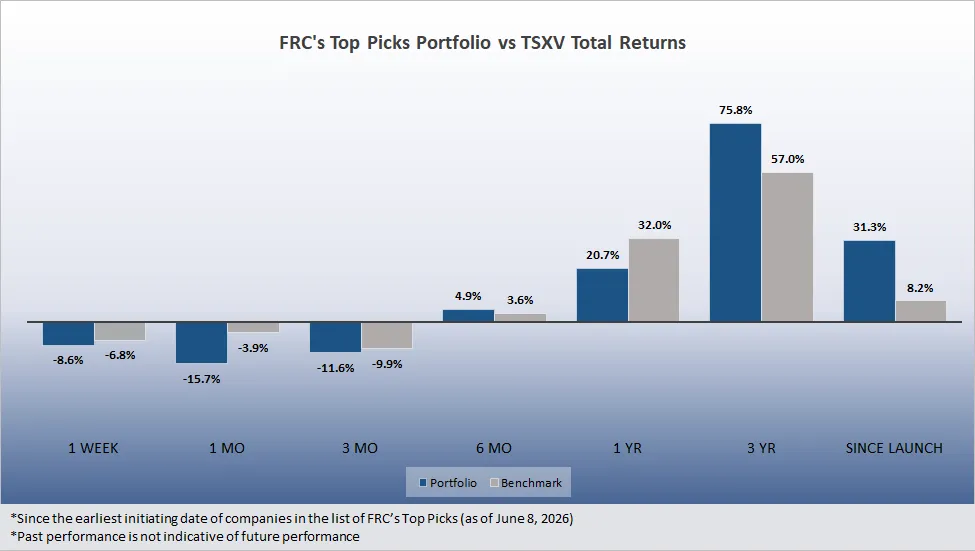
Last week, our Top Picks portfolio returned -8.6% vs -6.8% for the benchmark (TSXV). With ~60% of our picks in the resource sector, recent weakness in resource stocks has weighed on our short-term performance (one year and less).
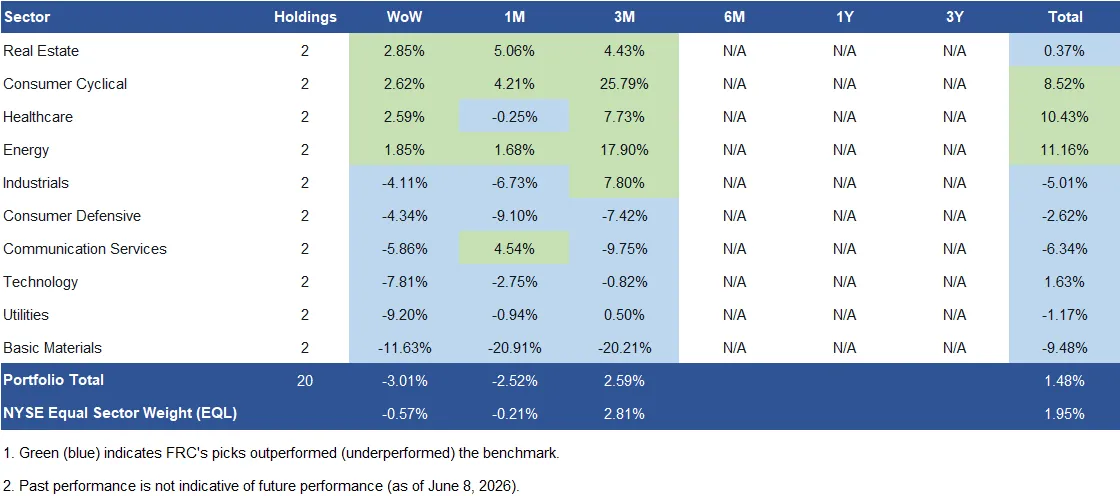
Last week, our Fair Value Model portfolio returned -3.0% vs -0.6% for the benchmark (NYSE Equal Sector Weight/EQL). While we underperformed across all four reviewed periods, our portfolio would have significantly outperformed over the past three months and since inception excluding the impact of resource stocks. Visit our website to view our full list of Model Picks by sector.
In this edition, we highlight recent developments from companies under coverage, including junior resource companies focused on copper, gold, helium, and graphite. We also introduce Gensource Potash Corporation, a Saskatchewan-based potash developer a potash developer with attractive project economics, a scalable growth strategy, and a potentially transformational financing catalyst.
*Past performance is not indicative of future performance.
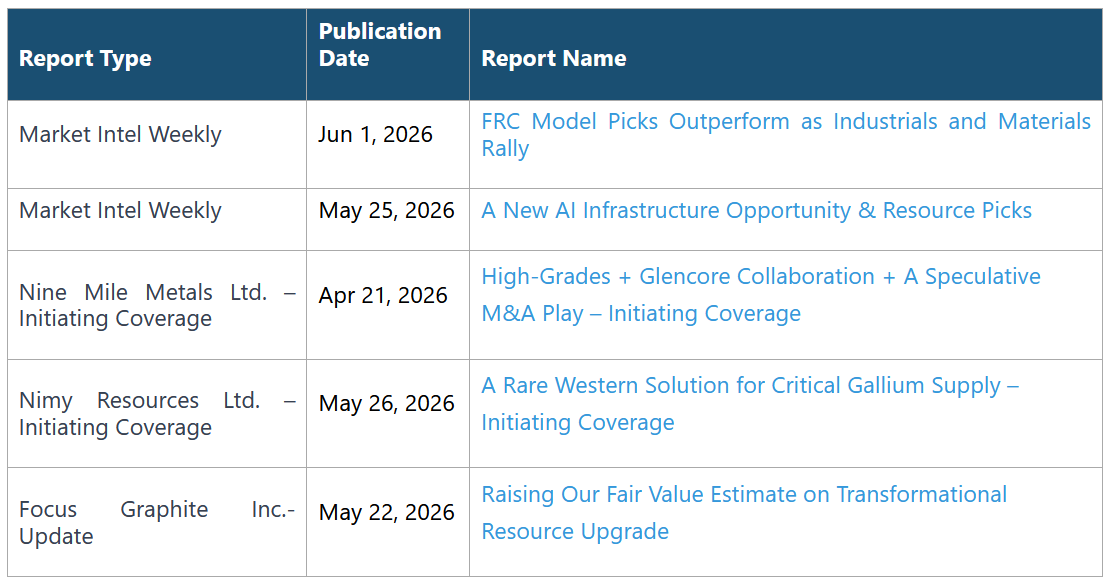
Last Week’s Five Most-Read Reports
Updates on Resource Companies Under Coverage
Denarius Metals Corp. (DMET.NE)
PR Title: Proposes Major Debt-for-Equity Restructuring
Analyst Opinion: Mixed
Analyst Comment: DMET announced a proposal to retire all of its convertible debentures through a share conversion, eliminating $190M in principal, interest, and gold-premium obligations. The plan would see the issuance of ~225M shares, nearly doubling the current share count. Management and insiders own approximately 26% of the debentures, aligning their interests with both shareholders and debenture holders.
Based on this scenario, we estimate our fair value would decline from $1.96 to $1.45/share due to dilution. However, we believe the transaction materially strengthens the balance sheet, preserves cash for growth, and reduces financing risk. As a result, our overall conviction in the stock would improve despite the lower fair value estimate. We will publish a detailed report if the proposal is approved.
DMET is ramping up gold-silver production at Zancudo in Colombia, and targeting first production from its Aguablanca nickel-copper project in Spain next year.
PR Title: Announced a $3.50M equity financing
Analyst Opinion: Positive
Analyst Comment: Proceeds will be used to fund Eskay’s upcoming 5,000 m drill program on its Corey-Eskay property in B.C.’s Golden Triangle, targeting several high-priority gold and polymetallic targets that have returned encouraging results from previous exploration. These targets may be linked to a larger gold-copper system similar to other major discoveries in the region.
We note that the project is located in one of the world’s richest mining districts, surrounding the past-producing Eskay Creek mine, and bordering projects owned by large miners. While the project does not yet have a resource estimate, our March 2026 report provides a preliminary assessment of its exploration potential.
Blue Star Helium Limited (BNL.AX)
PR Title: Secures Helium Offtake Agreement
Analyst Opinion: Positive
Analyst Comment: BNL owns helium projects in Colorado, and recently commenced production at its flagship Galactica project. The company is currently ramping up output and is targeting the start-up of a second project later this year.
BNL has entered into a three-month helium offtake agreement with an undisclosed publicly listed U.S. industrial gases company with a multi-billion-dollar MCAP. We view the agreement as an important validation of both the helium product and the Galactica project, while also potentially laying the foundation for a longer-term relationship that could provide greater revenue stability.
We are looking forward to initial production and operating data over the coming quarters, which could serve as key catalysts for the stock.
PR Title: Secures $1.38M in Canadian Government Funding
Qualified Person: Réjean Girard, P.Geo., President of IOS Geosciences Inc., a consultant to Focus Graphite
Analyst Opinion: Positive
Analyst Comment: FMS secured up to $1.38M in non-dilutive funding from Natural Resources Canada to advance road and power infrastructure planning for its Lac Knife graphite project in Quebec. We view this as another strong endorsement of Lac Knife, following the $14M in federal funding received last year. We believe these government-backed investments validate the project’s strategic importance, help de-risk development, and could support future financing and partnership opportunities.
A feasibility study estimates an after-tax NPV8% of $286M for Lac Knife vs FMS’ MCAP of $52M. In our view, the market is not fully reflecting the value of Lac Knife, and assigns little to no value to the company’s second project, Tétépisca, which hosts one of the world’s largest and highest-grade graphite resources.
PR Title: Discovers a New Mineralized Zone at the Blue Lake Project in Quebec
Qualified Person: Jacqueline Gauthier, P.Geo., VP Exploration of Cupani Metals
Analyst Opinion: Positive
Analyst Comment: Cupani announced a new Cu-Ni-PGE discovery, with results from the first two holes of a six-hole drill program returning significant grades, including 2.35 m at 1.74% CuEq, and 0.5 m at 1.32%. For context, most copper mines globally operate at grades of 0.3%-1.0%, with higher grades generally supporting stronger project economics.
The discovery, located 1.3 km southeast of the historical Blue Lake mineralized zones (which hosts a relatively high-grade unverified resource), confirms that mineralization extends well beyond the known area.
While Blue Lake remains an early-stage exploration project, we believe these results highlight the potential for a large mineralized system. Importantly, the property hosts numerous undrilled targets, providing multiple opportunities for future discoveries.
Gensource Potash Corporation (GSP.V)
PR Title: Early Due Diligence Highlights (All figures in C$ except commodity prices, which are in US$)
Qualified Person: Mike Ferguson, P.Eng., President & CEO of Gensource Potash
Analyst Opinion: Positive
Analyst Comment: We have commenced due diligence on GSP, and expect to initiate coverage in the coming weeks. The company controls potash assets in Saskatchewan, one of the world’s premier potash-producing regions, accounting for roughly one-third of global supply. GSP is fast-tracking its first project to production, and aims to become one of the world’s lowest-cost producers.
Potash is a critical fertilizer ingredient, and industry fundamentals remain highly favorable. Prices have risen 12% YoY to $405/t, supported by a fourth consecutive year of demand growth, and ongoing supply constraints. Supply tightness reflects sanctions on Belarus and Russia, which account for ~35% of global production, rising geopolitical tensions in the Middle East, where Israel and Jordan together produce ~10% of global output, elevated U.S.–Canada trade risks, and project delays. Global demand is forecast to grow 2–3% in 2026, and prices are expected to remain elevated due to continued supply pressures, geopolitical uncertainties, and trade risks.
Here are three key factors that have stood out in our due diligence:
- High-Quality, Strategic Asset:GSP’s flagship Tugaske project benefits from a large, high-grade NI 43-101 compliant (independently verified) resource, excellent infrastructure access, and a strategic location just 360 km from the U.S. border. The project has an offtake agreement covering 100% of planned production, providing strong third-party validation of its quality and economics. The project’s strategic location is increasingly important following potash’s addition to the U.S. Critical Minerals List in 2025.
- Attractive Economics and Scalable Growth:Unlike conventional potash mines that require billions in capital, GSP utilizes a scalable modular mining process that lowers capital costs, reduces environmental impacts, and accelerates development. A single 250,000-tonne per annum (tpa) module is expected to have operating costs of just $62/t, and all-in delivered costs of $116/t, implying substantial margins at current potash prices. An independent feasibility study estimated an after-tax NPV8% of $313M for a single module, compared to GSP’s MCAP of $66M, and an enterprise value of $73M. The company’s resource base can support at least 12 modules, providing significant long-term expansion potential.
III. Potential Strategic Financing Catalyst: GSP recently signed an exclusivity agreement with a large undisclosed ASEAN conglomerate that contemplates fully funding the construction of a 500,000 tpa operation. We believe a definitive agreement, if signed, would be a transformational milestone, potentially securing project financing, significantly de-risking the project, and accelerating its path to construction and production.
Our upcoming report will provide a detailed analysis, including our rating, fair value estimate, sensitivity analysis, and key risks and catalysts.
FRC Top Picks
Last week, our portfolio returned -8.6% vs -6.8% for the benchmark (TSXV). With ~60% of our picks in the resource sector, recent weakness in resource stocks has weighed on our short-term performance (one year and less). However, our picks continue to outperform over the long term, both over the past three years, and since inception. Visit our website to view our full list of Top Picks by sector.
Performance by Sector
Source: FRC
The table below highlights last week’s top five performers, led by Giga Metals Corporation (+6%), which is advancing a large nickel project in B.C., that is also prospective for copper, platinum, and palladium. We believe Mitsubishi Corporation’s 15% stake in Giga’s project underscores its potential.
FRC Fair Value Model Picks
Last week, our portfolio returned -3.0% vs -0.6% for the benchmark (NYSE Equal Sector Weight/EQL). While we underperformed across all four reviewed time periods, weakness in resource stocks was the primary drag on performance. Excluding the resource sector, our portfolio would have significantly outperformed over the past three months and since inception. Visit our website to view our full list of Model Picks by sector.
To view the complete report, click on the button above.
*Disclaimers – Annual fees ranging from $15,000 to $35,000 have been paid to FRC by Giga Metals Corporation, DLP Resources, Enterprise Group, Builders Capital Mortgage, Olympia Financial Group, Gensource Potash, Cupani Metals, Focus Graphite, Blue Star Helium, Eskay Mining, Denarius Metals, Nimy Resources, and Nine Mile Metals for research coverage and distribution of reports. FRC or companies with related management, and Analysts, do not hold shares/securities in the companies mentioned in this report.
**We have selected these companies based SOLELY on our screening tool and fair value feature. We have not looked into company or industry specific factors that could affect the stocks. This portfolio and updates are for information, educational, and entertainment purposes only. We want to see how a hypothetical portfolio picked largely using our fair value algorithm would fair against a passive index. Before investing in anything, you should do your own due diligence and speak to a professional advisor. FRC and/or its analysts may hold positions in one or more of the holdings.
The opinions expressed in this report are the true opinions of the analyst(s) about any companies and industries mentioned. Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The companies listed above are covered by FRC under an issuer-paid model, where fees have been paid to FRC to commission this report and research coverage. This creates a potential conflict of interest which readers should consider. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time. To subscribe for real-time access to research, visit https://www.researchfrc.com/plans for subscription options. This report contains “forward looking” statements. Forward-looking statements regarding the Company, industry, and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company’s products/services in the marketplace; acceptance in the marketplace of the Company’s new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company’s periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated, and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
