
[stock_market_widget type=”card” template=”basic2″ assets=”SGML” realtime=”true” api=”yahoo-finance”]
Lithium has spent the past few years swinging between extremes, and 2026 has done little to calm things down. After a brutal slide that took battery grade lithium carbonate prices in China from roughly $21,000 (150,000 yuan per tonne) at their 2022 peak to under $8,300 per tonne by mid 2025, the market reversed hard. A suspension at a major Chinese lepidolite mine and an abrupt export ban on lithium concentrate from Zimbabwe squeezed supply, and prices climbed again, touching roughly $25,156 per ton by April 2026, more than double where they sat only months earlier. S&P Global expects global demand for lithium chemicals to rise 13.5% in 2026 while supply grows a slower 9.9%, narrowing a surplus that has weighed on the sector for years.
That backdrop matters because most lithium producers spent the downturn cutting costs, delaying expansions, or idling mines rather than growing output. Against that pattern, Sigma Lithium Corporation (NASDAQ: SGML) delivered news this week that ran counter to the sector’s cautious mood.
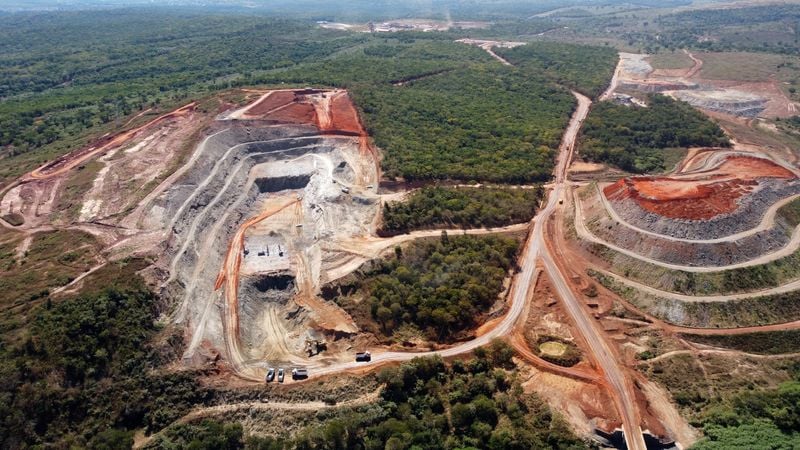
The company, which mines and processes spodumene ore into battery grade concentrate at its Grota do Cirilo operation in Brazil, reported second quarter 2026 production of 35,000 tonnes of high-grade lithium concentrate. That figure came in 6% above its own guidance of 33,000 tonnes, a gap the company attributed to a mining operations upgrade completed earlier this year, along with a shift toward running its own mining fleet rather than relying on contractors, a change it calls primarization.
The company’s processing plant also performed above plan during the quarter, recovering 70% of the lithium contained in the ore and delivering roughly 20% yield. Sigma Lithium said its mining fleet reached full operating capacity during the period, supported by a revised mine plan, and that the upgrade should make future output more predictable rather than just larger. Management is targeting an annualized rate of 240,000 tonnes from its current operation, with plans to add a second processing plant within the next year and potentially a third, which together would lift capacity toward 770,000 tonnes by the end of 2027.
Cost estimates released alongside the production figures point to an all in sustaining cost near $710 per tonne for the current phase of operations, falling to roughly $610 per tonne once the later expansion phases are running. At lithium prices between $1,500 and $2,500 per tonne, the company has sketched out a wide range of potential cash flow outcomes for investors to weigh, from $130 million on the low end to over $1.1 billion on the high end across its full expansion plan. Full financial results for the quarter are due out on August 14, 2026.
The bigger story here is really about what is happening across the lithium industry rather than any single company. Electric vehicles still account for the majority of lithium demand, and global EV sales are projected to top 25 million units this year, but the more interesting shift is happening in energy storage. Utilities building out battery systems to balance solar and wind power now account for roughly 15% of total lithium consumption, a share that keeps growing as data centers and grid operators buy batteries to smooth out electricity loads. Heavy duty electric trucks add another steady source of demand on top of that. Meanwhile, supply remains fragile. Zimbabwe’s export restrictions, uncertainty around when the suspended Chinese mine will restart, and the general reluctance of Australian producers to reopen mothballed operations after years of losses have all kept the market on edge.
None of this guarantees lithium prices stay elevated. Analysts remain split, with some expecting further supply growth from Africa and restarted Australian mines to cap prices, and others pointing to a structural deficit taking hold later in the decade. What Sigma Lithium’s second quarter shows is narrower but still notable: when a company that is actually producing, not just planning to produce, beats its own numbers during a period when much of the industry is retrenching, it tends to draw attention from people trying to figure out which lithium names can hold up through the next stretch of volatility.
