
PLEASE REVIEW THE DISCLAIMER ON THE BOTTOM OF THE PAGE
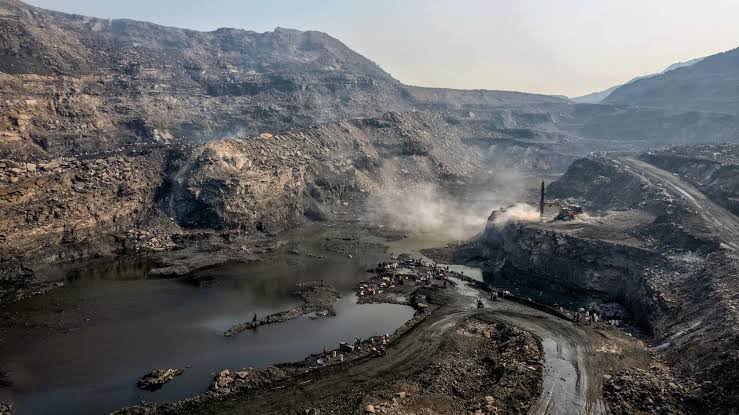
Copper is trading like a metal short on friends. Chilean mines are sputtering under water shortages and labor disputes, Washington’s own tariff writers have gone quiet past their self-imposed June 30th deadline, and London Metal Exchange (LME) warehouse stocks have drained nearly a fifth in five weeks, yet the metal that is supposed to read the pulse of the global economy is being yanked in every direction by a war that has nothing to do with mining at all. That tension defines small and micro-cap resource stocks this month: genuine, structural tightness in copper and uranium, unfolding underneath a tape whipsawed by Brent’s climb back above $86 a barrel on renewed U.S. strikes against Iran and the reimposed naval blockade of the Strait of Hormuz. The Russell 2000 shrugged off the noise long enough to touch a record above 3,046 on July 1st, its best run since 1991, before sliding back toward the 2,950 to 2,980 range as investors reassess how much geopolitical risk small caps can carry. Gold, meanwhile, is doing the opposite of what the headlines suggest, sitting near $4,067 an ounce and well off its January peak above $5,600, as softer June inflation data fights the safe haven bid for the metal’s attention.
The month’s defining story is the tug of war between a reignited Middle East conflict and cooling inflation data. Brent crude climbed back above $86 per barrel after the U.S. resumed strikes on Iran and reimposed a naval blockade near the Strait of Hormuz, reversing roughly a third of the second quarter’s decline. Softer June CPI, which showed headline inflation slowing to 3.5%, briefly lifted gold and eased Federal Reserve rate hike expectations, though markets still price roughly even odds of a September hike given oil driven inflation risk. Small cap miners with domestic production and low all in sustaining costs continued to outperform speculative explorers, extending the rerating trend that has defined 2026’s small cap resurgence.
WTI’s story is tighter than the headlines suggest. Cushing, Oklahoma, the futures contract’s delivery point, fell to roughly 19 million barrels in mid June, the lowest since October 2014, before a modest rebuild to about 19.4 million barrels by July 3rd. Commercial crude inventories stood at 409.7 million barrels for the week ended July 10th, still about 6% below the five year average even after ten straight weeks of draws finally broke with a small build. Refiners are running hard, with utilization near 96% and crude inputs above 17 million barrels a day. The EIA’s July outlook, published just before this week’s renewed strikes, had projected Brent easing to a $74 average in the third quarter on the assumption that the U.S. Iran memorandum would hold; WTI instead pushed back above $80 as that truce unraveled. For small and micro-cap oil and gas producers, elevated prices and thin domestic storage cushions have kept realizations, and hedging appetite, firm.
Investor appetite remains concentrated in producers with tangible output, particularly in copper, uranium, and helium, while non-producing juniors continue to lag absent near term catalysts. Uranium held a tight range near $85 to $86 per pound through the period, supported by continued utility contracting expectations and hyperscaler nuclear demand from technology companies building AI data centers. Silver has pulled back hard to the $58 to $59 range from a May peak near $90, as the geopolitical risk premium that inflated bullion unwound faster than industrial demand from solar and semiconductor manufacturing could backfill it. Industry analysts continue to flag structural supply deficits extending into the 2030s given multi year mine development timelines. Lithium carbonate has stabilized after its first quarter surge as Chinese and Australian producers resumed idled capacity, though prices remain well above year ago levels on continued EV and grid storage demand.
The broader commodity basket beneath copper and uranium tells its own story. Nickel has round tripped hard, dropping from a two year high near $19,350 a tonne in May to roughly $16,600 to $16,800 now, as Indonesia signals it may loosen its RKAB mining quota to 360 million tonnes at a late July review, defusing the supply deficit narrative that drove the spring rally. Rare earths moved the opposite direction: China’s Rare Earth Price Index climbed to 271.9 in early July, with the NdPr alloy benchmark up more than 21% for the month and dysprosium up over 25%, as Beijing’s licensing regime keeps heavy rare earth material scarce outside China. Iron ore rebounded to roughly $100 to $105 per tonne after a sharp June selloff, supported by a planned strike at BHP’s Port Hedland terminal and Chinese restrictions on lower grade Fortescue product. Thermal coal drifted back below $130 per tonne as muted Indian import demand offset the energy complex’s broader Hormuz driven firmness. Potash remained the fertilizer market’s steadiest performer, with North American muriate of potash near $310 to $380 per ton, up roughly 20% year over year on tight Canadian supply, even as BHP’s Jansen project in Saskatchewan continues to run over budget ahead of mid 2027 first production. Henry Hub natural gas firmed modestly into the $3.20 to $3.30 range on rising summer cooling demand.
Freeport-McMoRan Inc. (NYSE: FCX) remains the primary large cap beneficiary of any eventual domestic copper tariff premium, while Cameco Corporation (NYSE: CCJ) continues to be cited by institutional desks as a top nuclear fuel pick heading into the back half of 2026. Among small caps, Uranium Energy Corp. (NYSE American: UEC) advanced plans through its United States Uranium Refining and Conversion Corp. subsidiary for a new domestic conversion facility, adding to its Wyoming and Texas in situ recovery production base, though shares have pulled back from 52 week highs amid a broader valuation reset across the sector. Hycroft Mining Holding Corporation (NASDAQ: HYMC) published an updated technical report in early June outlining a resource base of roughly 16.4 million ounces of gold and 562 million ounces of silver, following its addition to the Russell 3000 Index in late May, a milestone that has begun drawing incremental institutional coverage to the debt free explorer.
Mako Mining Corp. (NYSE American: MAKO) and Amerigo Resources Ltd. (OTCQX: ARREF) continued steady production from their respective Nicaragua and Chile operations, benefiting from firm gold and copper prices even as diesel and input costs stayed elevated on the oil rally. BHP Group Limited (NYSE: BHP) and Rio Tinto Group (NYSE: RIO) remain focused on selective critical minerals acquisitions rather than greenfield development, a dynamic that continues to favor derisked junior targets as acquisition candidates. Equity issuance across the small cap complex stayed selective, concentrated in companies with near term production milestones, while the helium market stayed an acute standalone supply story, with Gulf export disruption tied to the Hormuz standoff and steady semiconductor, MRI, and quantum computing demand reinforcing the strategic value of North American helium assets in Saskatchewan and Nevada.
Zoom out, and the throughline for the month is a market where policy uncertainty and geopolitical risk are doing more to move prices day to day than fundamentals alone, even as those fundamentals remain the more durable story underneath the noise. Capital is rewarding operators over promoters: producers with real output, clean balance sheets, and near term catalysts kept outperforming speculative names, and a small cap index setting records despite a volatile macro backdrop is not the behavior of a market pricing in imminent trouble. The open risk is that any one of the unresolved questions hanging over this cycle, whether on the policy side or the geopolitical side, could resolve suddenly and move prices well before the sector’s next monthly review. For small and micro cap resource investors, that argues for staying selective and favoring companies that can control their own outcomes over ones dependent on a single headline breaking the right way.
Disclosure: This report is published the second Tuesday of each month for informational purposes only and does not constitute investment advice, a solicitation, or a recommendation to buy or sell any security. Small and micro-cap mining and natural resources equities carry substantial risk, including price volatility, liquidity constraints, and potential loss of principal. Company references are illustrative only. The publisher and affiliates may hold positions in securities mentioned herein. Readers should consult a qualified financial advisor before making investment decisions. All data sourced from publicly available third-party providers and is not independently verified. Past performance is not indicative of future results. Reproduction without prior written consent is prohibited. © 2026 All rights reserved.
