
Author: Atrium Research October 16, 2026
Nicholas Cortellucci, CFA | Equity Research Analyst | [email protected] | 647-391-3314
Luca Perna | Equity Research Associate | [email protected] | 647-969-1027
PLEASE REVIEW THE DISCLOSURES AT THE BOTTOM OF THE PAGE
What you need to know:
-
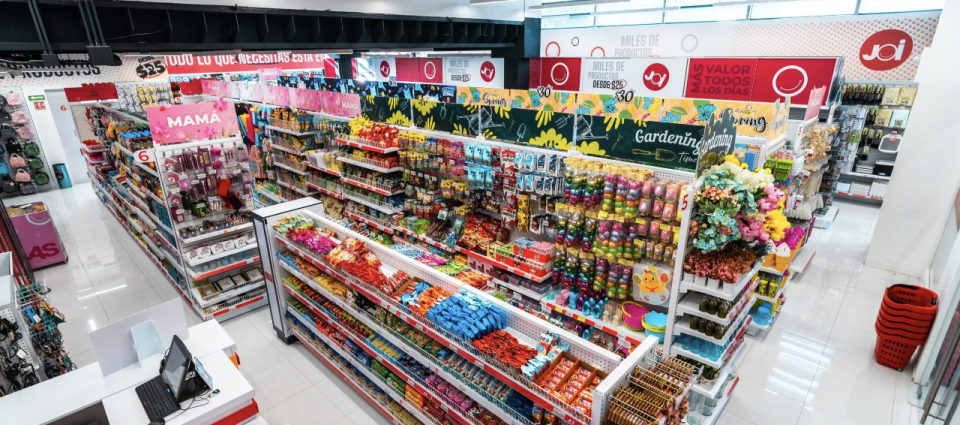
PesoRama is planning to open five new JOi Dollar Plus stores by the end of November, bringing the network to a total of 54 stores.
-
The Company closed its $28.4M bought deal financing at $0.60/share, including the partial exercise of the over-allotment option, funding >50 new stores.
-
Quilvest Capital Partners fully exited Tiendas 3B for a ~49x return, highlighting what a scaled Mexican discount retailer can be worth.
Yesterday, PesoRama (PESO:TSXV, PSSOF:OTCQX) announced the upcoming opening of five new JOi Dollar Plus stores, with stores #50 and #51 scheduled for October and stores #52, #53, and #54 for November. This marks quick execution on the newly raised capital, with more to come. Store #50 represents PESO’s fifth store in Puebla, while the remaining four expand the Company’s presence across the greater Mexico City area, including Toreo Parque Central in Naucalpan, a major retail destination with ~200 establishments and 1.3M visitors monthly. This will bring PESO to 54 stores by the end of November, compared to our model which assumed 66 stores by fiscal year-end. We are maintaining our BUY rating and target price of $1.60/share on PesoRama.
Bought Deal Financing On October 14ᵗʰ, PESO closed its previously announced bought-deal public offering, led by Canaccord Genuity, issuing 47.28M common shares at $0.60 per share for gross proceeds of ~$28.4M. This included the partial exercise of the underwriters’ over-allotment option, up from the base deal of $25.0M (41.67M shares) announced on October 5ᵗʰ. Proceeds will be used to continue the expansion of the JOi DOLLAR PLUS store network across Mexico and for general working capital. This is a major improvement on PESO’s last equity financing in April, when it raised $10M at $0.35/unit including a half warrant.
Given the cost to open a store of ~$0.5M, this should allow PESO to open >50 stores. This compares to our expectation of 13 stores to open in Q4 (reaching 66 total by fiscal year-end) and 64 in FY28 (reaching 130 by fiscal year-end), providing ample runway and growth funding.
Case Study – Tiendas 3B A few weeks ago, Quilvest Capital Partners announced that it has fully exited its position in BBB Foods Inc. (TBBB:NYSE), the operator of Tiendas 3B, returning US$1.1B to its investors, for a ~49x return. Quilvest first invested in BBB Foods in 2004, when it had one store and aimed to bring the European hard discount grocery model to Mexico. The company now operates ~3500 stores and grew revenue 39% in Q2/26 and achieved 20% same-store sales growth. In 2024, BBB Foods listed on the NYSE, and is up >150% since its IPO. TBBB now trades at a premium valuation of 38.2x 2026E EBITDA and 21.1x 2027E EBITDA.
As we noted in our initiation with regard to 3B (read here), the growth in the Mexican discount retail segment has been almost entirely grocery-led, and nobody has yet scaled a general dollar merchandising store. PESO is taking a similar approach to 3B, bringing a format from other countries into an underserved market. While the two formats are different, 3B shows that Mexico can support a discount retailer scale, and the market will reward it.
Catalysts
-
Quarterly Financial Results (Including Breakeven EBITDA) – Ongoing
-
New Store Opening Announcements – Ongoing
To view the complete report, click on the button above.
Analyst Certification
Each authoring analyst of Atrium Research on this report certifies that (i) the recommendations and opinions expressed in this research accurately reflect the authoring analyst’s personal, independent and objective views about any and all of the designated securities discussed (ii) no part of the authoring analyst’s compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views expressed in the research, (iii) to the best of the authoring analyst’s knowledge, she/he is not in receipt of material non-public information about the issuer, (iv) the analyst does not own common shares, options, or warrants in the company under coverage, (v) the analysts adhere to the CFA Institute guidelines for analyst independence, and (vi) this report belongs to the CFA Institute.
Atrium Research Ratings System
BUY: The stock is expected to generate returns of over 20% over the next 24 months.
HOLD: The stock is expected to generate returns of 0-20% over the next 24 months.
SELL: The stock is expected to generate negative returns over the next 24 months.
NOT RATED (N/R): Atrium does not provide research coverage on the respective company.
COVERED COMPANIES: 55
About Atrium Research
Atrium Research provides institutional quality company sponsored research on public equities in North America. Our investment philosophy takes a 3-5 year view on equities currently being overlooked by the market. Our research process emphasizes understanding the key performance metrics for each specific company, trustworthy management teams, and an in-depth valuation analysis. For further information on our team, please visit https://www.atriumresearch.ca/team.
General Information
Atrium Research Corporation (ARC) has created and distributed this report. This report is a general discussion of the merits and risks of a security or securities only, was prepared for general circulation, is not in any way meant to be tailored to the needs and circumstances of any recipient and does not provide investment recommendations specific to individual investors. As such, the securities discussed in this report may not be suitable for all investors and investors must make their own investment decisions based upon their specific investment objectives and financial situation, utilizing their own financial advisors as they deem necessary.
This report is based on information we considered reliable; we have not been provided with any material non-public information by the company (or companies) discussed in this report. We do not represent that this report is accurate or complete and it should not be relied upon as such; further any information in this report is subject to change without any formal or type of notice provided. Investors should consider this report as only one factor in their investment decisions; this report is not intended as a replacement for investor’s independent judgment.
ARC is not a CIRO registered dealer and does not offer investment-banking services to its clients. ARC (and its employees) do not own, trade or have a beneficial interest in the securities of the companies we provide research services for and does not serve as an officer or Director of the companies discussed in this report. ARC does not make a market in any securities. This report is not disseminated in connection with any distribution of securities and is not an offer to sell or the solicitation of an offer to buy any security in any jurisdiction where such an offer or solicitation would be illegal.
ARC does not make any warranties, expressed or implied, as to the results to be obtained from using this information and makes no express of implied warranties for particular use. Anyone using this report assumes full responsibility for whatever results they obtain. This report does not constitute a personal recommendation or take into account any financial or investment objectives, portfolio holdings, strategy, financial situations or needs of individuals. This report has not been prepared for any particular individual or institution. As such, any advice or recommendation in this report may not be suitable for a particular recipient. ARC assumes recipients of this report are capable of evaluating the information contained herein and of exercising independent judgment. A recipient of this report should not make any investment decision without first considering whether any advice or recommendation in this report is suitable for the recipient based on the recipient’s particular circumstances and, if appropriate or otherwise needed, seeking professional advice, including tax advice. ARC does not perform any suitability or other analysis to check whether an investment decision made by the recipient based on this report is consistent with a recipient’s investment objectives, portfolio holdings, strategy, financial situation, or needs. Past performance is not an indication or guarantee of future results, future returns are not guaranteed, and loss of original capital may occur. By providing this report, ARC does not accept any authority, discretion, or control over the management of the recipient’s assets. Any action taken by the recipient of this report, based on the information in the report, is at the recipient’s sole judgment and risk. The recipient must perform his or her own independent review of any prospective investment. Neither ARC nor any person employed by ARC accepts any liability whatsoever for any direct or indirect loss resulting from any use of its research or the information it contains.
This report contains “forward-looking” statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Such statements involve a number of risks and uncertainties such as competition, market demand, and the company’s (and management’s) ability to correctly forecast financial estimates. As a result, the actual results, events, performance or achievements of the financial product may be materially different from those expressed or implied in such statements. Please see the Company’s MD&A “Risk Factors” Section for a more complete discussion of company specific risks for the company discussed in this report. Any opinion or estimate constitutes the preparer’s best judgment as of the date of preparation, and is subject to change without notice. ARC assumes no obligation to maintain or update this report based on subsequent information and events.
ARC is receiving a cash compensation from PesoRama Inc. for 12-months of research coverage. This report was disseminated on behalf of PesoRama Inc. ARC retains full editorial control over its research content. ARC does not have investment banking relationships and does not expect to receive any investment banking driven income. ARC reports are primarily disseminated electronically and, in some cases, printed form. Electronic reports are simultaneously available to all recipients in any form. This report or any portion hereof may not be copied, reprinted, sold, or redistributed or disclosed by the recipient or any third party, by content scraping or extraction, automated processing, or any other form or means, without the prior written consent of ARC. Any unauthorized use is prohibited. Neither ARC nor any of its respective directors, officers or employees is responsible for guaranteeing the financial success of any investment, or accepts any liability whatsoever for any direct, indirect or consequential damages or losses arising from any use of this report or its contents.
To receive future reports on covered companies please visit https://www.atriumresearch.ca/research or subscribe on our website.
This report has been prepared independently of any issuer of securities mentioned herein and not as agent of any issuer of securities. No ARC personnel have authority whatsoever to make any representations or warranty on behalf of the Company. Any comments or statements made herein are those of ARC.
The information contained herein is not, and under no circumstances is to be construed as, an offer to sell securities described herein, or solicitation of an offer to buy securities described herein, in Canada or any province or territory thereof. Any offer or sale of the securities described herein in Canada will be made only under an exemption from the requirements to file a prospectus with the relevant Canadian securities regulators, if applicable, and only by a dealer properly registered under applicable securities laws or, alternatively, pursuant to an exemption from the dealer registration requirement in the relevant province or territory of Canada in which such offer or sale is made. The information contained herein is under no circumstances to be construed as investment advice in any province or territory of Canada and is not tailored to the needs of the recipient. To the extent that the information contained herein references securities of an issuer incorporated, formed or created under the laws of Canada or a province or territory of Canada, any trades in such securities must be conducted through a dealer registered in Canada. No securities commission or similar regulatory authority in Canada has reviewed or in any way passed judgment upon this research report, the information contained herein or the merits of the securities described herein, and any representation to the contrary is an offence.
The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
