
Every time someone tops up an online gaming account, buys a concert ticket, or checks out from a small web store, a chain of companies quietly moves the money. Card networks set the rules, banks hold the accounts, and payment platforms sit in the middle, approving transactions, screening for fraud, and settling funds with merchants. It is one of the largest corners of financial services, and one of the most crowded.
The sums involved are enormous. McKinsey estimates the global payments industry generated about $2.5 trillion in revenue in 2024 from roughly 3.6 trillion transactions. Revenue grew about 7% a year from 2019 to 2024, but growth cooled to 4% in 2024 as interest rates peaked and fee pressure built.
That slowdown has continued. The firm’s newest report puts 2025 revenue near $2.6 trillion, up only about 3%, and it expects growth of around 4% a year through 2030. Its warning was blunt: companies that rely mainly on processing volume face rising pressure on margins as cheaper alternative networks spread.
For a mid-sized platform, that creates a hard equation. Scale lowers the cost of each transaction, so the giants can price aggressively. Smaller players often survive by specializing in niches that larger rivals find too complex or too risky, such as online betting, gaming, and cross-border digital wallets. Those niches can carry higher fees, but they also bring regulatory scrutiny, heavy marketing costs, and customers who leave quickly when a cheaper option appears.
Debt adds another layer. Many payment companies were assembled through acquisitions financed with borrowed money. When an acquired business stops growing as planned, the company must cut the value it carries on its balance sheet, a step known as a goodwill impairment. It does not drain cash, but it is an admission that earlier expectations were too optimistic.
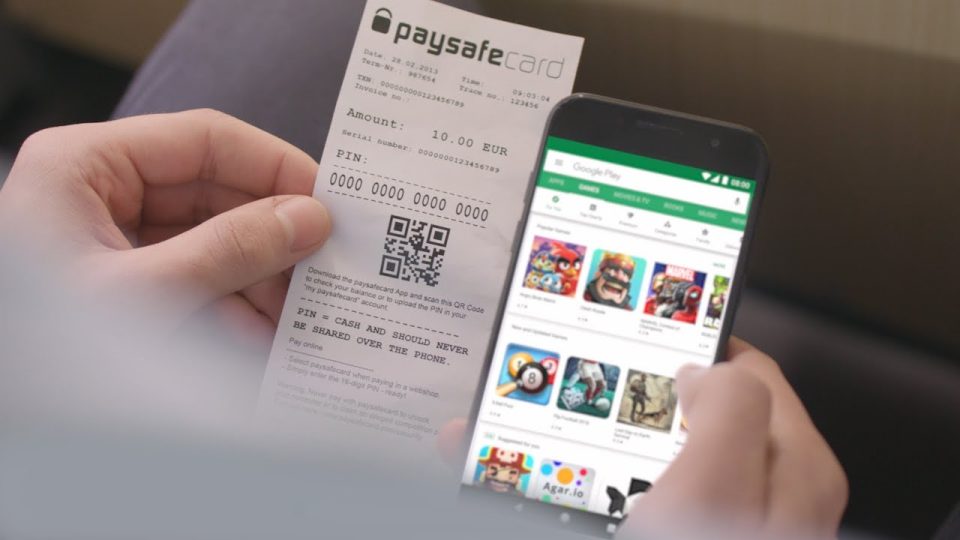
That is the backdrop for this morning’s selloff at Paysafe Limited (NYSE: PSFE). The London-based company, which went public by merging with a special purpose acquisition company, describes itself as a payments platform built for the experience economy. It runs two businesses: Merchant Solutions, which processes payments for merchants, and Digital Wallets, which includes Skrill, NETELLER and paysafecard.
Shares fell more than 32% at the open of the market this morning, following third-quarter results released before the bell. Revenue rose about 1% to $439.6 million, short of the roughly $448 million analysts expected. Adjusted earnings came in at $0.44 per share against expectations of $0.55, and down from $0.70 a year earlier. Adjusted EBITDA, a common measure of operating profit, dropped 17% to $105.7 million, which the company tied to business mix, ongoing investment, and severance costs.
The bottom line looked far worse. Paysafe reported a net loss of $247.5 million, including the $203.3 million goodwill impairment. Interest expense also rose $7.5 million because of higher rates following the August 12th refinancing, which pushed most of its loan maturities out to 2030.
The outlook did the most damage. Paysafe now expects full-year revenue between $1.761 billion and $1.771 billion and adjusted earnings between $1.45 and $1.54 per share. In August, management had guided to adjusted earnings between $1.90 and $2.03.
Leverage is why the cut stings. At the end of June, net debt stood at about 5.3 times annual adjusted EBITDA, and management called lowering that ratio the most important near-term driver of shareholder value, with a medium-term target of 3.5 times. Weaker earnings make that path longer, even if the debt balance itself keeps shrinking.
Whether today marks a bargain or a trap depends on something the market cannot yet see. A much cheaper stock can reward patient holders if the company steadies its margins and keeps paying down debt. If earnings keep slipping, the same debt load leaves little room for error, and the burden of proof now rests with management.
