
Author: Atrium Research November 19, 2026
Nicholas Cortellucci, CFA | Equity Research Analyst | [email protected] | 647-391-3314
Luca Perna | Equity Research Associate | [email protected] | 647-969-1027
PLEASE REVIEW THE DISCLOSURES AT THE BOTTOM OF THE PAGE
What you need to know:
-
ADF signed the largest contract in its history, totalling $602M. This compares to its prior PF backlog of $776M and market cap of $491M (based on yesterday’s close).
-
The contract is for a technology company, supporting a new mega manufacturing building in the northeastern U.S. This will be completed on a fast-tracked schedule over 18 months, beginning in a few weeks.
-
We are largely increasing our estimates for FY28, resulting in an increased target price of $31.00/share.
This morning, ADF Group (DRX:TSX) announced the signing of the largest contract in its history, totalling $602M. This brings the backlog to over $1B, also an all-time high. This builds on the strong momentum ADF has been seeing in the business and supports rapid growth accelerating over the coming year. We are maintaining our BUY rating and increasing our target price to $31.00/share (previously $21.00/share).
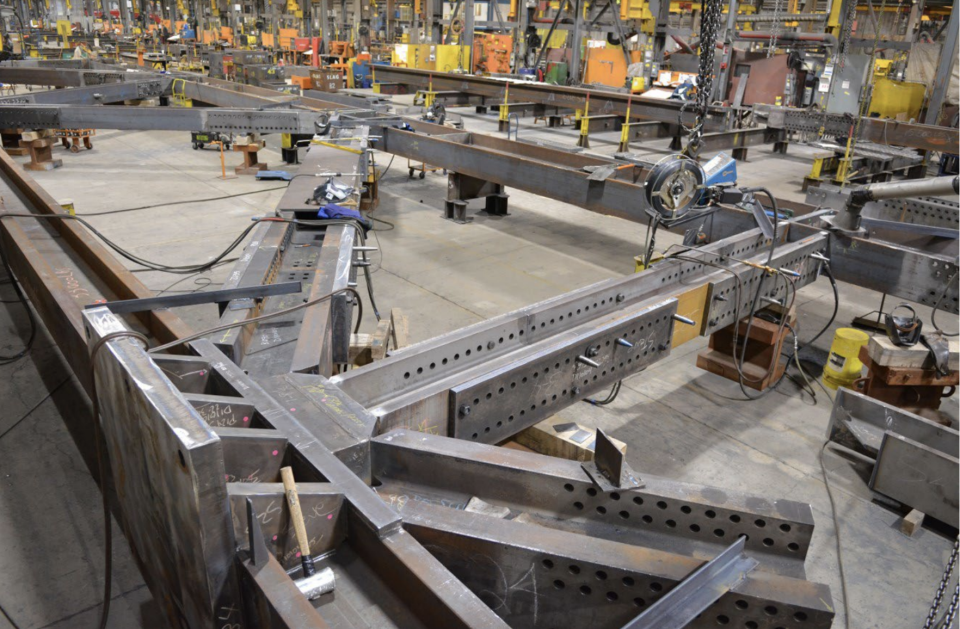
The project is in the northeastern United States for a new mega manufacturing building in the information technology sector for an internationally renowned company. The work includes connection engineering, fabrication, and industrial coating. The project will be the largest of its kind in the sector and speaks to ADF’s unique ability to work on large-scale and fast-tracked projects, a space in the industry that its peers cannot compete in.
Management stated that its teams are ready and mobilized, and it will make a $10M capital investment at the Terrebonne facility to support this contract. The project is on a fast-tracked schedule, beginning in the coming weeks in Terrebonne and extending just over 18 months.
Conference Call Takeaways
-
PF backlog is just under $1.4B. Client could come back for more contracts; project is multi-phase.
-
Standard margins on the project. Not complex engineering but has an aggressive schedule. Will utilize the robotics for ~70% of the project, increasing efficiency. No new capacity needed; other bays still operating as normal with room to grow.
-
Tariffs will be absorbed by the client.
-
Starting with the engineering and design process. Steel is procured by ADF and included in the $602M. Procuring the steel right away (as usual), the project will require 400 tonnes of steel at its peak.
-
Only 2 bids on this project. ADF was chosen due to experience, robotics, bonding capacity, balance sheet, and delivery schedule.
-
Capex is for re-engineering a portion of storage area into production space. However, the project will be cashflow positive throughout.
Our Take This contract is a major win for DRX and its shareholders, and to us, is reminiscent of the work ADF did for its Midwest pharma client (rumoured to be Eli Lilly) in FY25, yet this is even larger scale. That project was also completed on a fast-track schedule and resulted in the massive FY25 print of $339.6M in revenue and $91.3M in EBITDA. The stock went on a 700% run during this project execution (plus others) and traded at highs of >8x forward EBITDA (read note here).
Today’s contract is the $602M spread across six quarters, for an incremental $100M of revenue per quarter; more than doubling ADF’s current quarterly revenue of ~$80M. For our model, we assume a small contribution in Q4, before fully contributing to FY28. We are baking in some conservatism given we do not know the cadence of delivery and the fact that there are always potential for delays, now forecasting $748M in FY28 revenue vs. $451M prior (see Estimate Revisions below). We forecast lower gross margins than in our last note due to the scale of the project, but still higher than this year’s levels. We are now assuming $130M in EBITDA and $88M in earnings in FY28. Going forward, we are watching for quarterly execution on deliveries and repeatability of orders in the technology sector to reaffirm long-term growth.
To view the complete report, click on the button above.
Analyst Certification
Each authoring analyst of Atrium Research on this report certifies that (i) the recommendations and opinions expressed in this research accurately reflect the authoring analyst’s personal, independent and objective views about any and all of the designated securities discussed (ii) no part of the authoring analyst’s compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views expressed in the research, (iii) to the best of the authoring analyst’s knowledge, she/he is not in receipt of material non-public information about the issuer, (iv) the analyst does not own common shares, options, or warrants in the company under coverage, (v) the analysts adhere to the CFA Institute guidelines for analyst independence, and (vi) this report belongs to the CFA Institute.
Atrium Research Ratings System
BUY: The stock is expected to generate returns of over 20% over the next 24 months.
HOLD: The stock is expected to generate returns of 0-20% over the next 24 months.
SELL: The stock is expected to generate negative returns over the next 24 months.
NOT RATED (N/R): Atrium does not provide research coverage on the respective company.
COVERED COMPANIES: 55
About Atrium Research
Atrium Research provides institutional quality company sponsored research on public equities in North America. Our investment philosophy takes a 3-5 year view on equities currently being overlooked by the market. Our research process emphasizes understanding the key performance metrics for each specific company, trustworthy management teams, and an in-depth valuation analysis. For further information on our team, please visit https://www.atriumresearch.ca/team.
General Information
Atrium Research Corporation (ARC) has created and distributed this report. This report is a general discussion of the merits and risks of a security or securities only, was prepared for general circulation, is not in any way meant to be tailored to the needs and circumstances of any recipient and does not provide investment recommendations specific to individual investors. As such, the securities discussed in this report may not be suitable for all investors and investors must make their own investment decisions based upon their specific investment objectives and financial situation, utilizing their own financial advisors as they deem necessary.
This report is based on information we considered reliable; we have not been provided with any material non-public information by the company (or companies) discussed in this report. We do not represent that this report is accurate or complete and it should not be relied upon as such; further any information in this report is subject to change without any formal or type of notice provided. Investors should consider this report as only one factor in their investment decisions; this report is not intended as a replacement for investor’s independent judgment.
ARC is not a CIRO registered dealer and does not offer investment-banking services to its clients. ARC (and its employees) do not own, trade or have a beneficial interest in the securities of the companies we provide research services for and does not serve as an officer or Director of the companies discussed in this report. ARC does not make a market in any securities. This report is not disseminated in connection with any distribution of securities and is not an offer to sell or the solicitation of an offer to buy any security in any jurisdiction where such an offer or solicitation would be illegal.
ARC does not make any warranties, expressed or implied, as to the results to be obtained from using this information and makes no express of implied warranties for particular use. Anyone using this report assumes full responsibility for whatever results they obtain. This report does not constitute a personal recommendation or take into account any financial or investment objectives, portfolio holdings, strategy, financial situations or needs of individuals. This report has not been prepared for any particular individual or institution. As such, any advice or recommendation in this report may not be suitable for a particular recipient. ARC assumes recipients of this report are capable of evaluating the information contained herein and of exercising independent judgment. A recipient of this report should not make any investment decision without first considering whether any advice or recommendation in this report is suitable for the recipient based on the recipient’s particular circumstances and, if appropriate or otherwise needed, seeking professional advice, including tax advice. ARC does not perform any suitability or other analysis to check whether an investment decision made by the recipient based on this report is consistent with a recipient’s investment objectives, portfolio holdings, strategy, financial situation, or needs. Past performance is not an indication or guarantee of future results, future returns are not guaranteed, and loss of original capital may occur. By providing this report, ARC does not accept any authority, discretion, or control over the management of the recipient’s assets. Any action taken by the recipient of this report, based on the information in the report, is at the recipient’s sole judgment and risk. The recipient must perform his or her own independent review of any prospective investment. Neither ARC nor any person employed by ARC accepts any liability whatsoever for any direct or indirect loss resulting from any use of its research or the information it contains.
This report contains “forward-looking” statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Such statements involve a number of risks and uncertainties such as competition, market demand, and the company’s (and management’s) ability to correctly forecast financial estimates. As a result, the actual results, events, performance or achievements of the financial product may be materially different from those expressed or implied in such statements. Please see the Company’s MD&A “Risk Factors” Section for a more complete discussion of company specific risks for the company discussed in this report. Any opinion or estimate constitutes the preparer’s best judgment as of the date of preparation, and is subject to change without notice. ARC assumes no obligation to maintain or update this report based on subsequent information and events.
ARC is receiving a cash compensation from ADF Group Inc. for 12-months of research coverage. This report was disseminated on behalf of ADF Group Inc. ARC retains full editorial control over its research content. ARC does not have investment banking relationships and does not expect to receive any investment banking driven income. ARC reports are primarily disseminated electronically and, in some cases, printed form. Electronic reports are simultaneously available to all recipients in any form. This report or any portion hereof may not be copied, reprinted, sold, or redistributed or disclosed by the recipient or any third party, by content scraping or extraction, automated processing, or any other form or means, without the prior written consent of ARC. Any unauthorized use is prohibited. Neither ARC nor any of its respective directors, officers or employees is responsible for guaranteeing the financial success of any investment, or accepts any liability whatsoever for any direct, indirect or consequential damages or losses arising from any use of this report or its contents.
To receive future reports on covered companies please visit https://www.atriumresearch.ca/research or subscribe on our website.
This report has been prepared independently of any issuer of securities mentioned herein and not as agent of any issuer of securities. No ARC personnel have authority whatsoever to make any representations or warranty on behalf of the Company. Any comments or statements made herein are those of ARC.
The information contained herein is not, and under no circumstances is to be construed as, an offer to sell securities described herein, or solicitation of an offer to buy securities described herein, in Canada or any province or territory thereof. Any offer or sale of the securities described herein in Canada will be made only under an exemption from the requirements to file a prospectus with the relevant Canadian securities regulators, if applicable, and only by a dealer properly registered under applicable securities laws or, alternatively, pursuant to an exemption from the dealer registration requirement in the relevant province or territory of Canada in which such offer or sale is made. The information contained herein is under no circumstances to be construed as investment advice in any province or territory of Canada and is not tailored to the needs of the recipient. To the extent that the information contained herein references securities of an issuer incorporated, formed or created under the laws of Canada or a province or territory of Canada, any trades in such securities must be conducted through a dealer registered in Canada. No securities commission or similar regulatory authority in Canada has reviewed or in any way passed judgment upon this research report, the information contained herein or the merits of the securities described herein, and any representation to the contrary is an offence.
The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
