

Atrium Mortgage Investment Corporation
Soft Lending Activity / Sector Tailwinds Outweigh Headwinds
Published: May 12, 2026
Author: FRC Analysts
Disclosure: Atrium Mortgage Investment Corporation has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions.
Company Details
Sector – Financial Services
Industry – Mortgage Finance
Trading Information
Trading information – AI.TO : TSX
Report Highlights
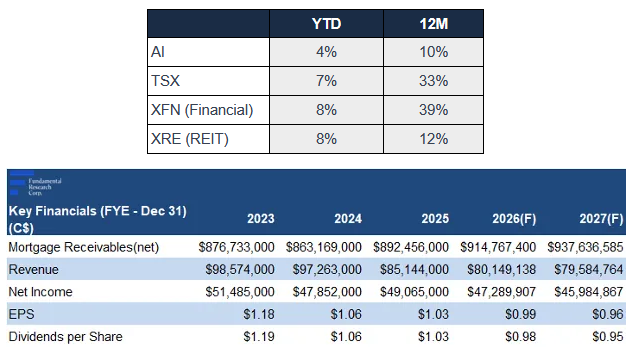
- Soft activity weighs on revenue; dividend maintained: Loan advances declined 62% YoY, marking the softest Q1 in more than a decade, driving a 2% QoQ decline in net mortgages outstanding to $871M. Revenue declined 10% YoY on lower rates, and came in 6% below our estimate. Net income increased 1% YoY, due to lower loan loss provisions, but was 4% below our estimate. Annual regular dividend held steady at $0.93/share.
- Cheaper borrowing offsets spread compression: AI’s lending rates have declined 250 bps since peaking in 2023 vs a 275 bps drop in the benchmark rate, indicating lower elasticity. Credit facility borrowing costs have also eased, partially offsetting spread compression.
- Macroeconomic backdrop: We expect rates to stay stable through 2026, as unemployment levels have eased since peaking in September 2025, and inflation remains moderate. A stable rate environment should support lower default risk, and improving mortgage origination momentum.
- Portfolio focus: Development and construction activity remains subdued amid lower immigration, weaker GDP growth, geopolitical uncertainty, and U.S. trade tensions. Management continues to shift toward lower-risk property types, including single-family residential, and income-producing commercial assets. AI also plans further expansion into Alberta and B.C., including a new Alberta office, which should improve geographic diversification, given Ontario currently represents over 90% of the portfolio.
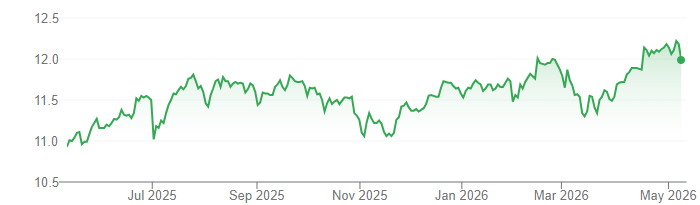
- Market positioning: Historically, declining rates have benefited MICs and financials. However, MICs have lagged broader financials over the past year (+10% YoY vs +39% YoY), and traded more in line with REITs (+12% YoY), reflecting continued weakness in residential real estate sentiment. We believe a gradual housing market recovery should support MIC stocks this year.
- 2026 Outlook: We now project a dividend of $0.98/share (previously $1.02/share), implying an 8.28% yield.
Price and Volume (1-year)
* Atrium Mortgage Investment Corporation has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions. All figures in C$ unless otherwise stated.
Loan advances declined 62% YoY, marking the softest Q1 in more than a decade, while repayments fell 47% YoY, driving a 2% QoQ decline in net mortgages outstanding to $871M
Portfolio Update
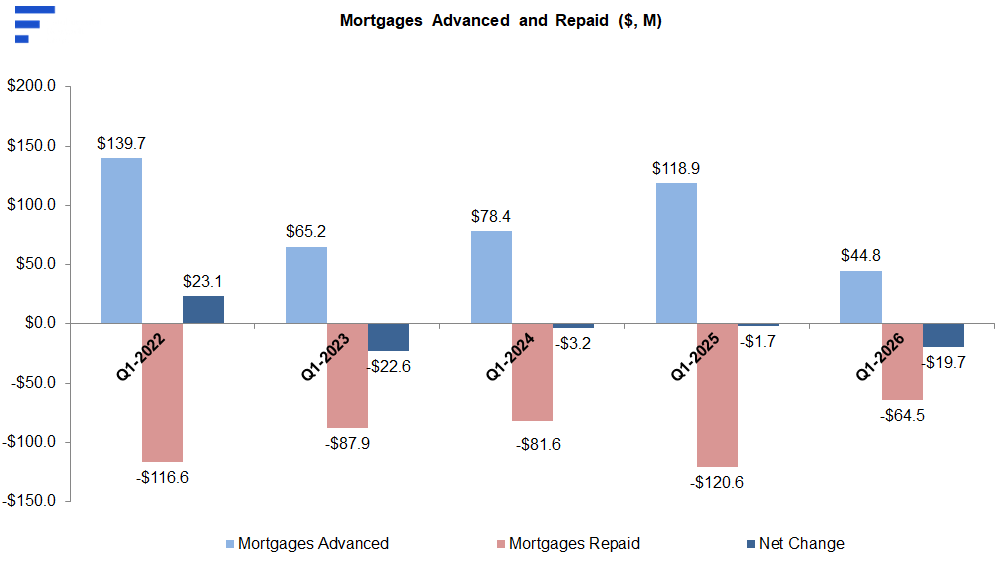
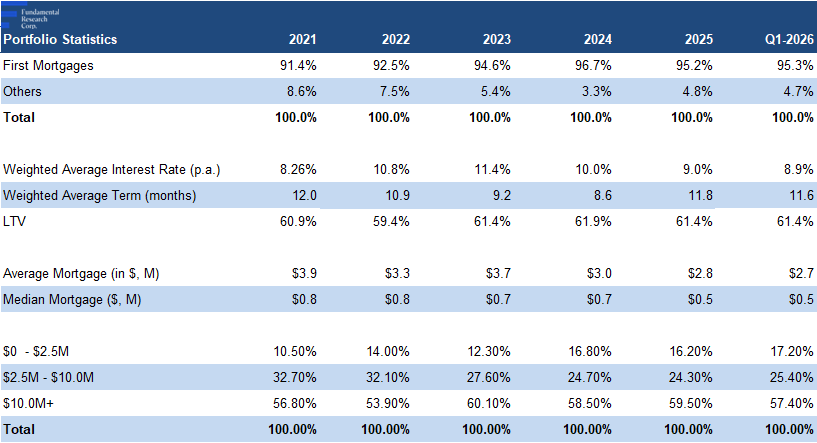
First mortgages and LTVs remained relatively stable QoQ
AI’s lending rates continued to ease following BoC rate cuts; since peaking in 2023, rates have declined 2.50 pp vs a 2.75 pp decline in the benchmark rate, suggesting AI’s rates are less elastic
Credit facility borrowing costs also declined QoQ, from 5.08% to 4.57%, partially offsetting spread compression
Source: Company Data / FRC
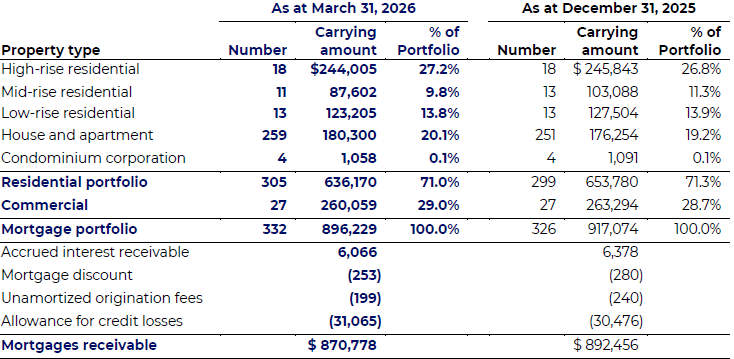
Exposure to property types remained unchanged, with continued focus on revenue-generating commercial properties, and built single-family units, relatively low risk segments vs development projects
Mortgages by Region
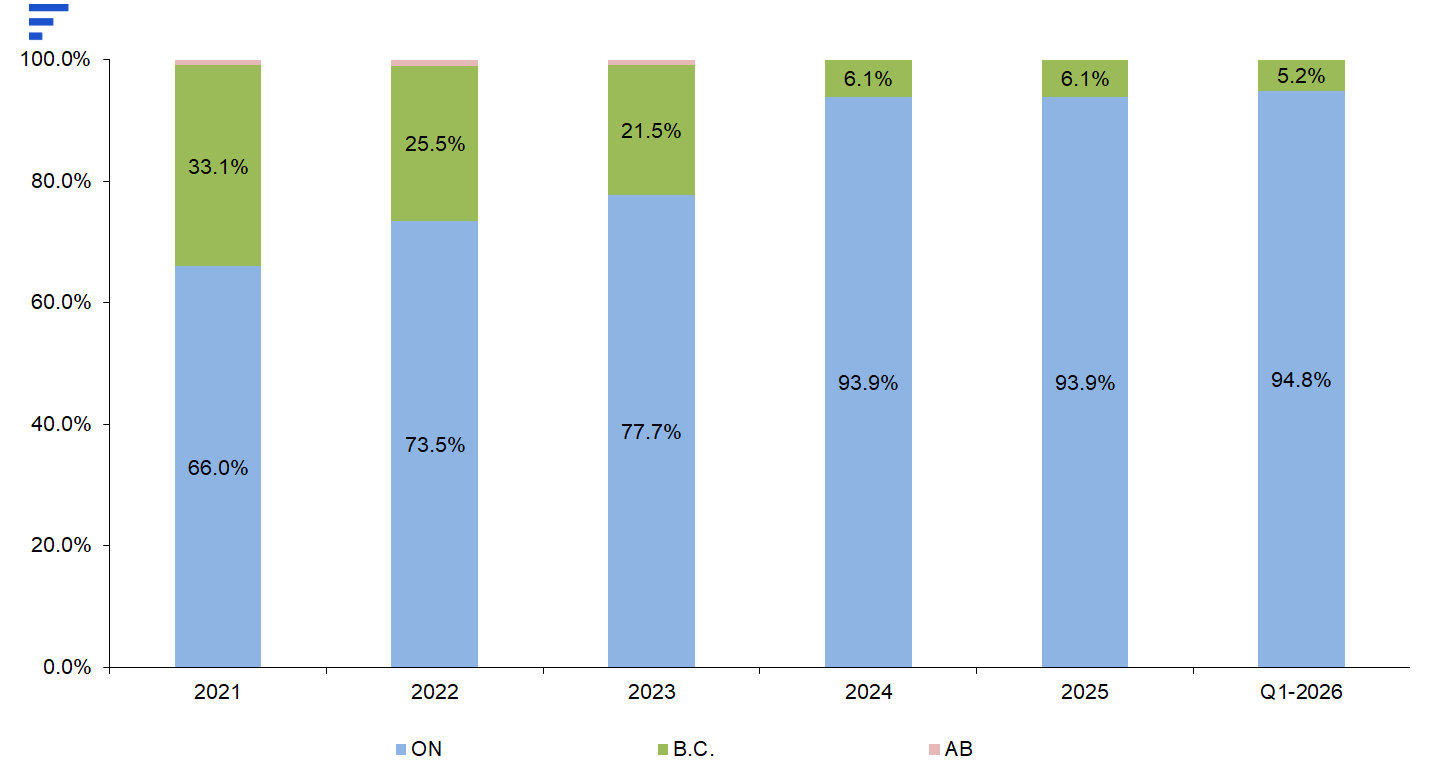
Continued to increase exposure to Ontario, weighing on geographic diversification
However, AI plans to expand further into Alberta and BC in coming quarters, including opening a new Alberta office to support grow
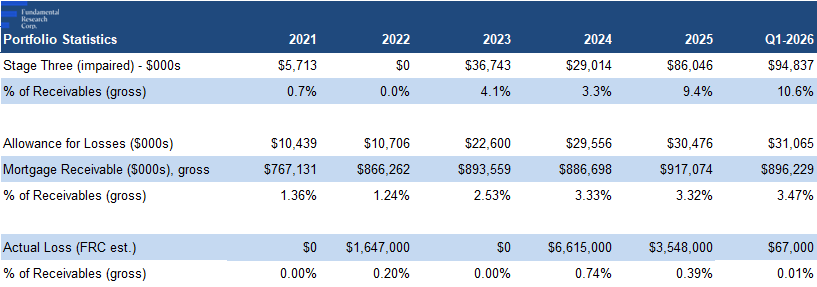
Stage three (impaired) mortgages rose 10% QoQ to $95M on one additional default
Source: FRC / Company
AI expects two loans ($41M) to be repaid or refinanced by May-end, which should reduce stage three exposure from 11% to 6% of total mortgages vs 9% at year-end 2025, and a historic average of 3%
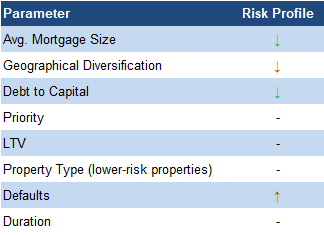
*Red (green) indicates an increase (decrease) in risk level.
Source: FRC
To view the complete report, click on the button above.
The opinions expressed in this report are the true opinions of the analyst(s) about any companies and industries mentioned. Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The companies listed above are covered by FRC under an issuer-paid model, where fees have been paid to FRC to commission this report and research coverage. This creates a potential conflict of interest which readers should consider. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time. To subscribe for real-time access to research, visit https://www.researchfrc.com/plans for subscription options. This report contains “forward looking” statements. Forward-looking statements regarding the Company, industry, and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company’s products/services in the marketplace; acceptance in the marketplace of the Company’s new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company’s periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated, and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
