

Gensource Potash Corporation
Redefining Potash Mining: A Game-Changing Partnership in the Making
Published: Jule 12, 2026
Author: FRC Analysts
Disclosure: Gensource Potash Corporation has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions.
Report Highlights
- Potential Near-Term Producer in a Tight Potash Market: GSP is advancing Tugaske, a high-grade potash project in Saskatchewan, the world’s largest potash-producing region and one of the world’s top mining jurisdictions. We believe the project is well positioned against a backdrop of: i) a 12% YoY increase in potash prices; ii) a fourth consecutive year of demand growth; iii) Russia/Belarus supply constraints (~35% of global production); iv) Middle East geopolitical risks (~10% of global production); v) Canada-U.S. trade uncertainty; and vi) delayed global supply additions.
- Experienced Team with Strong Shareholder Alignment: Management and directors own 10% of the company. The leadership team brings decades of experience from Nutrien and K+S, providing deep expertise in potash development, fertilizer operations, and capital markets.
- Modular Mining Could Be a Game Changer: GSP is advancing a modular potash mining model with significantly lower initial CAPEX (~$350M vs. multi-billion-dollar conventional mines), enabling faster, phased development, and potentially reducing financing risk. While the underlying technology and process are proven, the modular production model has yet to be demonstrated at commercial scale and remains subject to execution risk.
- Compelling Economics and Significant Upside: A 2021 bankable feasibility study generated an after-tax NPV8% of $454M for a single 250,000 tonne per annum (250 Ktpa) module. We believe the current resource could support 30+ modules, while management is conservatively targeting 12 modules (3 Mtpa). Applying the economics of a single module to 12 modules implies a potential after-tax NPV8% of $5.5B, versus GSP’s current MCAP of just $57M, highlighting a significant valuation disconnect.
- Strategically Positioned for U.S. Supply Security: The U.S. imports >90% of its potash, with Canada supplying ~80%. Since adding potash to its Critical Minerals List, the U.S. has funded strategic potash projects including one in Africa, highlighting the importance of secure supply. We believe GSP’s proximity to the U.S., direct rail access, and an offtake agreement with Helm Fertilizers, a leading North American fertilizer distributor, strengthens its strategic position.
- Potentially Transformational ASEAN Partnership: GSP has signed an agreement with a large undisclosed ASEAN conglomerate to evaluate a two-module (500 Ktpa) project, including long-term product offtake and potential full project funding, which could limit future shareholder dilution. A definitive agreement would represent a major validation of GSP’s modular strategy.
- Multiple Near-Term Catalysts: GSP is up 28% YoY, outperforming both the TSXV (+17%) and the S&P Fertilizers & Agricultural Chemicals Index (+8%). Key catalysts include an updated resource estimate and feasibility study, and a definitive agreement with the ASEAN partner, potentially including full project funding.
Risks
- Potash price volatility
- Permitting and construction delays
- Financing and strategic partner risk
- Unproven modular mining model
- Potential shareholder dilution
Price and Volume (1-year)
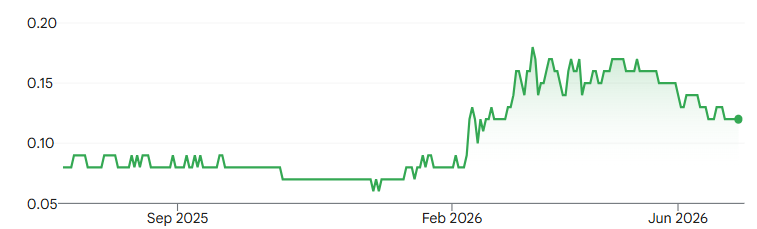
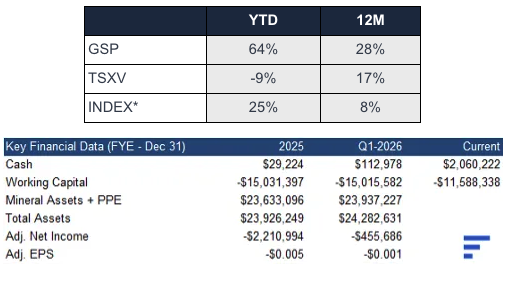
*Much of the working capital deficit relates to project partners and may be renegotiated. Discussions with the ASEAN partner could unlock significant project funding. Qualified Person: Mike Ferguson, P.Eng., President & CEO of Gensource Potash. Gensource Potash has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions. All figures in C$ except for commodity prices, which are in US$.
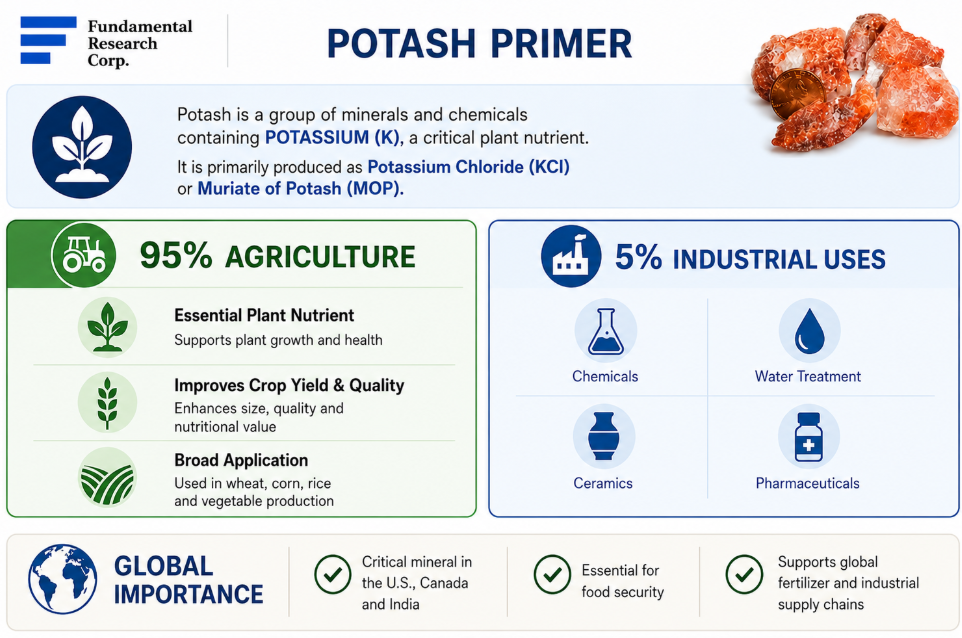
Source: FRC
To view the complete report, click on the button above
The opinions expressed in this report are the true opinions of the analyst(s) about any companies and industries mentioned. Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The companies listed above are covered by FRC under an issuer-paid model, where fees have been paid to FRC to commission this report and research coverage. This creates a potential conflict of interest which readers should consider. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time. To subscribe for real-time access to research, visit https://www.researchfrc.com/plans for subscription options. This report contains “forward looking” statements. Forward-looking statements regarding the Company, industry, and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company’s products/services in the marketplace; acceptance in the marketplace of the Company’s new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company’s periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated, and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
