

Overview
In our view, Klondike offers a rare combination of district-scale exploration potential, expanding hard rock resources, exceptional infrastructure advantages, and a meaningful non-dilutive royalty cash flow stream, an uncommon profile within the junior gold sector. With multiple catalysts expected through 2026–2027, we believe the Company is positioned for a material rerating as the market begins to recognize the scale and geological significance of the emerging hard rock system underlying the historic Klondike placer fields.
Redeveloping a Historic Gold District
Klondike Gold controls a 100% owned, 727 km² land package covering the core of the world famous Klondike district, which produced more than 20 million ounces of placer gold since the 1896 discovery at Bonanza Creek. Despite this extraordinary endowment, the primary hard rock source remained unidentified for more than a century. Klondike Gold’s recent work is changing that narrative.
In 2022, the Company delivered the first modern hard rock Mineral Resource Estimate (MRE) in the district, outlining 580,860 ounces of gold across the Lone Star and Stander zones, see Table 1. This milestone was supported by more than 45,000 meters of drilling and represents the first substantive confirmation of bedrock mineralization capable of explaining the district’s placer productivity.
Investment highlights
Tier 1 Jurisdiction and Infrastructure
- Immediate access to grid power, highways, and Dawson City services significantly reduces exploration and development costs.
- All in drilling costs of ~$350/meter ranks among the lowest globally for northern gold exploration. District scale geological potential
- Controls 727 km² across the historic Klondike district, source of over 20 million ounces of placer gold.
- First company to define a meaningful hard rock resource in the camp, confirming the long sought bedrock source. Resource growth and exploration momentum
- Current 580,860 ounce MRE expected to expand materially with nearly 30,000 meters of new drilling.
- Fully funded 2026 drill program targets Lone Star and Stander extensions ahead of a major 2026–2027 resource update. Royalty cash flow and strategic positioning
- Montana Creek placer royalty provides $1.5–2.0M expected 2026 cash flow, reducing dilution and funding exploration.
- Strong shareholder base includes major sector investors and aligned management, supporting long term project advancement.
We are initiating coverage on Klondike Gold Corp. with a BUY recommendation and a 12-month target price of $0.50 per share
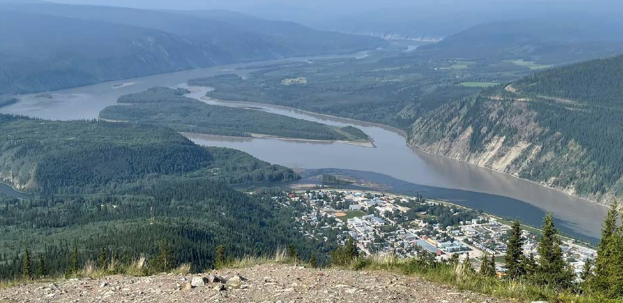
Lookout over Dawson City and the Yukon and Klondike Rivers. Source: Couloir Capital
