

Market Intel Weekly
Navigating Geopolitics, Finding Opportunity
Published: July 20, 2026
Author: FRC Analysts
Disclosure: Articles and research coverage are paid for and commissioned by issuers, except for those listed under the “FRC Fair Value Model Picks” section. See the bottom for other important disclosures, and issuer-specific information.
*Disseminated on behalf of Atrium Mortgage Investment, Zepp Health Corporation, Millennial Potash, Enterprise Group, Giga Metals Corporation, Enterprise Group Inc., Olympia Financial Group, Skyharbour Resources Ltd., Nine Mile Metals Ltd., Focus Graphite Inc., Doubleview Gold Corp., Argo Gold Inc., and Blue Star Helium Limited.
* All figures are in C$ unless otherwise noted, except for commodity prices, which are in US$.
Equity markets edged lower last week as escalating geopolitical tensions in the Middle East weighed on investor sentiment, despite softer-than-expected U.S. inflation data that pushed treasury yields and the US$ lower. Consumer cyclical, real estate, and energy led sector gains, while basic materials was the weakest-performing sector despite relatively stable metal prices.
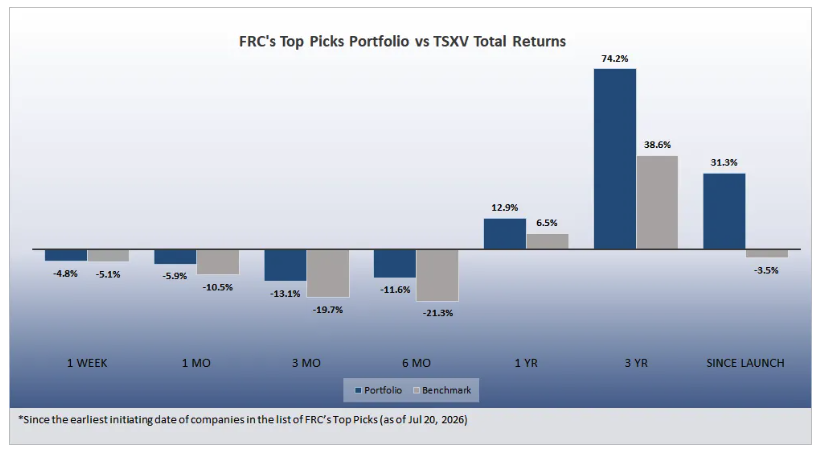
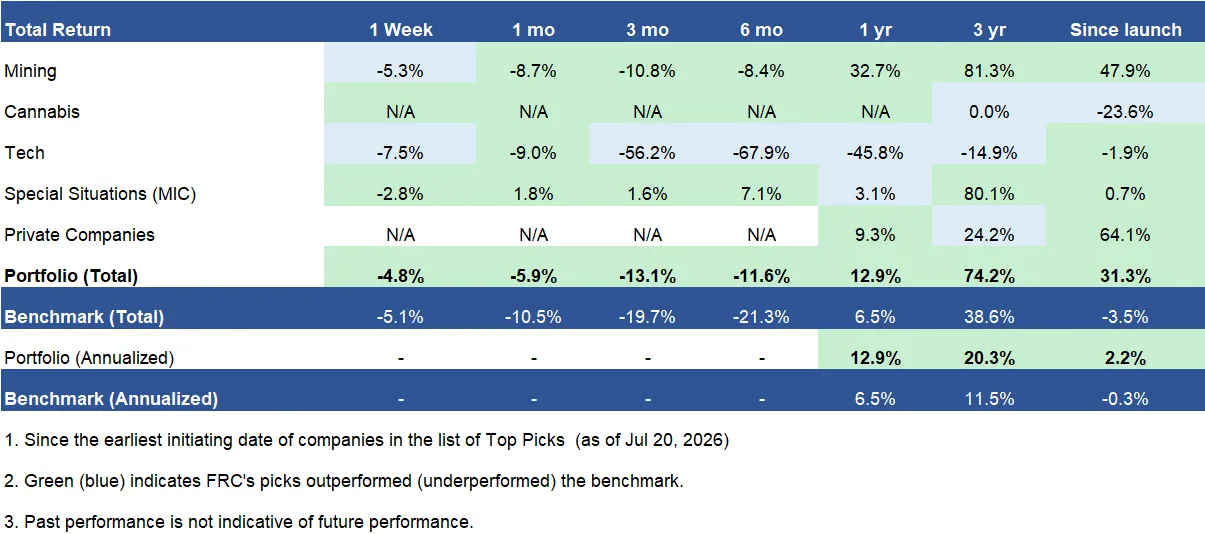
Last week, our Top Picks portfolio returned -4.8% vs -5.1% for the benchmark (TSXV). Our picks have outperformed the benchmark across all seven tracked periods.
Last week, our Fair Value Model portfolio returned 0.7% vs -0.3% for the benchmark (NYSE Equal Sector Weight/EQL). Our picks have outperformed the benchmark in two of the four tracked time periods.
This edition features Argo Gold’s undervalued producing oil asset, Blue Star Helium’s transition to commercial production, encouraging project updates from Doubleview Gold, Focus Graphite, Skyharbour Resources, and Nine Mile Metals, Olympia Financial’s earnings-accretive corporate restructuring, and Enterprise Group’s expanding customer adoption. Read on for our take on why these developments matter. As geopolitical tensions continue to influence markets, we believe these developments present compelling opportunities.
*Past performance is not indicative of future performance.
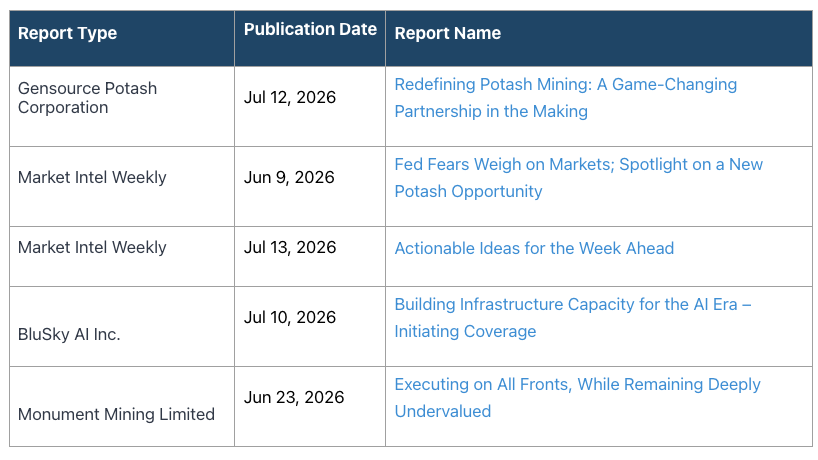
Last Week’s Five Most-Read Reports
Updates on Resource Companies Under Coverage
PR Title: Producing Oil Asset Remains Deeply Undervalued
Qualified Person: Michael Guo, PhD, PGeo, MG Geological Consulting Ltd.
Analyst Opinion: Positive
Analyst Comment:
In May 2026, Argo produced 2,514 bbls of oil (81 bpd; YTD average: 76 bpd), up 7% MoM, generating $274k in revenue (YTD monthly average: $204k), up 8% MoM. Since commencing production at its Sparky oil project in 2023, the company has remained profitable since 2024, with operating cash flow fully funding exploration and corporate costs, eliminating the need for shareholder dilution.
Argo offers exposure to gold, oil, and uranium, with mining investor Eric Sprott owning a 16% stake. Its producing oil asset carries an independent valuation of $15M vs a MCAP of just $6M, and an enterprise value of $7M. We believe the market is not fully recognizing the value of the producing oil asset, while assigning little to no value to its gold and uranium exploration assets.
Blue Star Helium Limited (BNL.AX)
PR Title: First Helium Sale Marks Commercial Production (All figures in US$)
Analyst Opinion: Positive
Analyst Comment:
BNL has reached a transformative milestone with its first helium sale, marking the completion of commissioning and the start of revenue generation from its 50%-owned Galactica-Pegasus project in Colorado. As production ramps up, and with a second helium project expected to come online later this year, we expect meaningful near-term production and cash flow growth.
At full build-out, we estimate the project could generate $82M in annual revenue, and $53M in operating profit. BNL trades at just 0.3x our operating profit estimate, versus >4x for peers, suggesting the market has yet to recognize its earnings potential.
PR Title: Drilling Progress Supports Resource Upgrade
Qualified Person: Tomasz Waruch, FAusIMM & Erik Ostensoe, P.Geo., Consulting Geologists for Doubleview Gold
Analyst Opinion: Positive
Analyst Comment:
All four holes from an ongoing drill program at its 100%-owned Hat project in B.C. intersected the targeted mineralized system, with assay results pending. The program is designed to improve resource confidence by potentially upgrading inferred resources to the higher-confidence measured and indicated categories. We view the latest results positively, as they indicate the program could lead to a meaningful resource upgrade.
Hat hosts a 10.4 Blb CuEq resource, well above the typical 2-6 Blb range for comparable projects. A recent PEA outlined a 25-year mine life, with an after-tax NPV5% of $7B. DBG currently trades at just ~7% of NPV, suggesting significant upside potential.
PR Title: Optimized Access Route Could Enhance Economics
Qualified Person: Réjean Girard, P.Geo. (QC), President of IOS Geosciences Inc., a consultant to Focus Graphite
Analyst Opinion: Positive
Analyst Comment:
FMS completed an access road study for its Lac Knife project in Quebec, identifying a preferred access route that is expected to require significantly less new road construction than the route assumed in the 2023 feasibility study. The optimized route has the potential to reduce infrastructure CAPEX, shorten construction timelines, and lower permitting risk, which could improve project economics.
Lac Knife hosts one of the world’s highest-grade graphite deposits, and is supported by a feasibility study, which estimates an after-tax NPV8% of $286M. With FMS trading at a MCAP of just $41M, we believe the shares do not fully reflect the value of Lac Knife, while assigning no value to the company’s Tétépisca project in Quebec, one of the world’s largest and highest-grade graphite deposits.
Skyharbour Resources Ltd. (SYH.V)
PR Title: New LOI Expands Partner-Funded Portfolio
Analyst Opinion: Positive
Analyst Comment:
SYH has entered into a non-binding letter of intent (LOI) to option its pre-resource stage Yurchison uranium property in Saskatchewan’s Athabasca Basin to Purecore Metals (CSE: PURE/MCAP: $23M). Yurchison is prospective for uranium, copper, zinc, and molybdenum mineralization. We view the announcement positively, as it further validates SYH’s prospect generator strategy by advancing non-core assets through partner-funded exploration.
SYH’s portfolio comprises 43 properties covering approximately 663,000 hectares. Assuming all current earn-in agreements are completed, option partners could fund over $76M in exploration expenditures, and provide over $45M in cash and share payments to SYH vs the current MCAP of $87M, highlighting the significant value of its partner-funded project portfolio.
Nine Mile Metals Ltd. (NINE.CN)
PR Title: Drilling Continues to Support Wedge Expansion Potential
Qualified Person: Gary Lohman, B.Sc., PGO, VP Exploration & Director for Nine Mile Metals
Analyst Opinion: Positive
Analyst Comment:
The third hole of an ongoing drill program at the historic Wedge mine intersected a 125 m mineralized interval, supporting the potential for a large volcanogenic massive sulphide (VMS) system. For context, such deposits are known for producing copper, silver, zinc, lead, and gold over long periods. While assays are pending, we view the results positively, as they indicate mineralization may continue at depth. Historical mining records suggest that >60% of the historical Wedge deposit may remain unmined at depth.
The Wedge property is one of four projects controlled by NINE in the Bathurst Mining Camp in New Brunswick, one of the world’s richest areas for VMS deposits. The company is working with Glencore to evaluate whether its material could be processed at Glencore’s Horne Smelter in Rouyn-Noranda, Quebec. Successful tests could open the door to a partnership, or potential M&A interest.
Updates on Financials, Technology, Energy, and Special Situations Companies Under Coverage
Olympia Financial Group Inc. (OLY.TO)
PR Title: Reorganization at an Attractive Implied Valuation
Analyst Opinion: Positive
Analyst Comment:OLY has entered a reorganization agreement to terminate its management agreements. OLY will pay ~$50M ($45M in cash + $5M shares), funded primarily through a credit facility. Management expects the transaction to simplify its compensation structure and reduce annual executive compensation from ~$18M to $3-$4M.
Based on expected annual savings of ~$15M, we estimate an implied valuation of just 3.3x, well below the financial services sector average of 11.5x (Source: S&P Capital IQ). While leverage will increase, we believe the debt is manageable given OLY’s debt-free balance sheet. Overall, we view the transaction as highly positive, driven by significant recurring cost savings, and an attractive valuation. The transaction is subject to shareholder, court, TSX, and regulatory approvals.
PR Title: Client Expansion Validates Power Solutions Strategy
Analyst Opinion: Positive
Analyst Comment:E announced that two undisclosed Canadian oil & gas producers, following successful initial deployments of its natural gas power solutions, have decided to expand their deployments with additional projects. We view this positively, as it validates the company’s value proposition, while demonstrating growing customer confidence in its power solutions. The announcement also supports management’s recent decision to rebrand the company as Evolution PowerX Corp.
Performance Methodology: The performance figures presented below are intended to measure our stock-picking effectiveness and do not represent the NAV or returns of a continuously managed investment portfolio. Results are based on equal notional investments in each pick and reflect the average performance of both current and exited positions over each time period shown. Performance is not time-weighted and excludes dividends. The selected benchmarks also exclude dividends, making the comparison consistent.
FRC Top Picks
Last week, our portfolio returned -4.8% vs -5.1% for the benchmark (TSXV). Our picks have outperformed the benchmark across all seven tracked time periods. Visit our website to view our full list of Top Picks by sector.
Source: FRC
The table below highlights last week’s top five performers, led by Giga Metals Corporation (+14%). Giga is advancing one of the world’s largest undeveloped nickel-cobalt projects in B.C.
To view the complete report, click on the button above
The opinions expressed in this report are the true opinions of the analyst(s) about any companies and industries mentioned. Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The companies listed above are covered by FRC under an issuer-paid model, where fees have been paid to FRC to commission this report and research coverage. This creates a potential conflict of interest which readers should consider. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time. To subscribe for real-time access to research, visit https://www.researchfrc.com/plans for subscription options. This report contains “forward looking” statements. Forward-looking statements regarding the Company, industry, and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company’s products/services in the marketplace; acceptance in the marketplace of the Company’s new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company’s periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated, and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
