
Author: Atrium Research November10, 2026
Ben Pirie | Equity Research Analyst | [email protected] | 647-688-9661
Nicholas Cortellucci, CFA | Equity Research Analyst | [email protected] | 647-391-3314
PLEASE REVIEW THE DISCLOSURES AT THE BOTTOM OF THE PAGE
What you need to know:
-
RIO reported its Q3/26 production and financial results outlining consolidated production of 12.3Koz Au, 95.3Koz Ag, and 9.6Mlb Cu.
-
RIO disclosed extreme weather impacts on Fenix’s ramp up at the end of September, so there are no surprises in this morning’s results.
-
Condestable continued to deliver consistent production, and adjusted financials came in slightly ahead of our expectations.
-
RIO will host a webinar on November 12ᵗʰ at 11AM ET to discuss this morning’s results and outlook.
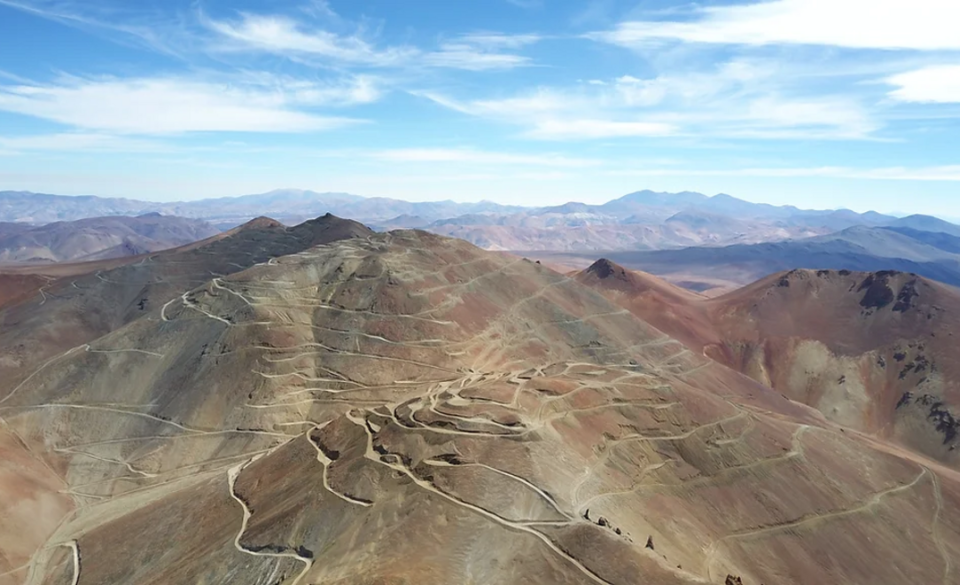
This morning, Rio2 (RIO:TSX, RIOFF:OTC) reported its Q3/26 production and financial results with consolidated production of 12.3Koz Au, 95.3Koz Ag, and 9.6Mlb Cu. RIO had already reported significant weather-related challenges in the quarter at Fenix, and results are largely as expected. The operation remains on track for commercial production this quarter. Through the ramp-up, Condestable is proving to be a steady contributor to RIO’s production profile, delivering another quarter of consistent production. Overall, financials were slightly ahead of our expectations after adjusting out a sizable fair value loss. We are maintaining our BUY rating and target price of C$5.75/share on Rio2.
Storms set back Fenix ramp-up. As previously disclosed in RIO’s September operations update (read here), extreme weather driven by a super El Niño significantly impacted the quarter, and production was expected to be roughly flat QoQ. Q3 gold production of 8.5Koz was broadly in line with our expectation of 8.8Koz, declining modestly from 9.1Koz in Q2 (-6%). The revised monthly projections released in September implied ~17Koz in Q4 for ~40Koz in 2026, and RIO has reiterated expectations for Fenix to ramp up to 20Ktpd and achieve commercial production in Q4. Q3 cash costs declined QoQ from $2,701/oz to $2,370/oz, compared to our forecast of $2,155/oz. Similarly, AISC declined from $2,872/oz in Q2 to $2,615/oz.
Steady performance at Condestable. The operation mined ~700Kt of ore at average grades of 0.72% Cu, 0.23 g/t Au, and 5.27 g/t Ag. ~686Kt processed was modestly below our 720Kt forecast (-5%), and copper recoveries of 88.8% remained marginally below expectations due to mining oxide ore at shallow depths, resulting in copper production of 9.6Mlb vs. our 10.5Mlb forecast (-8%); albeit, increasing QoQ from 9.3Mlb (+3%). Mining is migrating to deeper levels as the expanded haulage fleet is deployed. We were forecasting lower QoQ gold grades of 0.15 g/t, which remained roughly flat from 0.24 g/t in Q2, and was further bolstered by gold recoveries of 77.0% ahead of budget, resulting in gold production of 3.8Koz vs. our 2.8Koz estimate (+36%). Silver production contributed 93.9Koz vs. our 80.3Koz forecast (+17%). Q3’s cash costs and AISC of $2.62/lb and $3.40/lb modestly increased from $2.34/lb and $3.10/lb in Q2.
Financial Highlights
-
Q3 revenue of $115.4M increased +10% QoQ from $105.3M in Q2 and came in ahead of our $93.5M forecast by +23%.
-
Income from mining operations was $43.8M vs. $39.2M in Q2 (+12% QoQ) and our estimate of $37.5M.
-
Q3 EBITDA of ($1.8M) vs. $76.2M in Q2 and our forecast of $39.5M reflects a $41.1M fair value loss on stream obligations. This resulted from updating Condestable’s forecast for the planned expansion to 10Ktpd and extended mine life to 2041. Adjusted EBITDA of $50.0M beat our expectations.
-
Q3’s net income of ($28.2M) reflects the fair value loss. Adjusted net income of $22.4M beat our $17.5M forecast and $17.1M in Q2.
To view the complete report, click on the button above.
Analyst Certification
Each authoring analyst of Atrium Research on this report certifies that (i) the recommendations and opinions expressed in this research accurately reflect the authoring analyst’s personal, independent and objective views about any and all of the designated securities discussed (ii) no part of the authoring analyst’s compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views expressed in the research, (iii) to the best of the authoring analyst’s knowledge, she/he is not in receipt of material non-public information about the issuer, (iv) the analyst does not own common shares, options, or warrants in the company under coverage, (v) the analysts adhere to the CFA Institute guidelines for analyst independence, and (vi) this report belongs to the CFA Institute.
Atrium Research Ratings System
BUY: The stock is expected to generate returns of over 20% over the next 24 months.
HOLD: The stock is expected to generate returns of 0-20% over the next 24 months.
SELL: The stock is expected to generate negative returns over the next 24 months.
NOT RATED (N/R): Atrium does not provide research coverage on the respective company.
COVERED COMPANIES: 55
About Atrium Research
Atrium Research provides institutional quality company sponsored research on public equities in North America. Our investment philosophy takes a 3-5 year view on equities currently being overlooked by the market. Our research process emphasizes understanding the key performance metrics for each specific company, trustworthy management teams, and an in-depth valuation analysis. For further information on our team, please visit https://www.atriumresearch.ca/team.
General Information
Atrium Research Corporation (ARC) has created and distributed this report. This report is a general discussion of the merits and risks of a security or securities only, was prepared for general circulation, is not in any way meant to be tailored to the needs and circumstances of any recipient and does not provide investment recommendations specific to individual investors. As such, the securities discussed in this report may not be suitable for all investors and investors must make their own investment decisions based upon their specific investment objectives and financial situation, utilizing their own financial advisors as they deem necessary.
This report is based on information we considered reliable; we have not been provided with any material non-public information by the company (or companies) discussed in this report. We do not represent that this report is accurate or complete and it should not be relied upon as such; further any information in this report is subject to change without any formal or type of notice provided. Investors should consider this report as only one factor in their investment decisions; this report is not intended as a replacement for investor’s independent judgment.
ARC is not a CIRO registered dealer and does not offer investment-banking services to its clients. ARC (and its employees) do not own, trade or have a beneficial interest in the securities of the companies we provide research services for and does not serve as an officer or Director of the companies discussed in this report. ARC does not make a market in any securities. This report is not disseminated in connection with any distribution of securities and is not an offer to sell or the solicitation of an offer to buy any security in any jurisdiction where such an offer or solicitation would be illegal.
ARC does not make any warranties, expressed or implied, as to the results to be obtained from using this information and makes no express of implied warranties for particular use. Anyone using this report assumes full responsibility for whatever results they obtain. This report does not constitute a personal recommendation or take into account any financial or investment objectives, portfolio holdings, strategy, financial situations or needs of individuals. This report has not been prepared for any particular individual or institution. As such, any advice or recommendation in this report may not be suitable for a particular recipient. ARC assumes recipients of this report are capable of evaluating the information contained herein and of exercising independent judgment. A recipient of this report should not make any investment decision without first considering whether any advice or recommendation in this report is suitable for the recipient based on the recipient’s particular circumstances and, if appropriate or otherwise needed, seeking professional advice, including tax advice. ARC does not perform any suitability or other analysis to check whether an investment decision made by the recipient based on this report is consistent with a recipient’s investment objectives, portfolio holdings, strategy, financial situation, or needs. Past performance is not an indication or guarantee of future results, future returns are not guaranteed, and loss of original capital may occur. By providing this report, ARC does not accept any authority, discretion, or control over the management of the recipient’s assets. Any action taken by the recipient of this report, based on the information in the report, is at the recipient’s sole judgment and risk. The recipient must perform his or her own independent review of any prospective investment. Neither ARC nor any person employed by ARC accepts any liability whatsoever for any direct or indirect loss resulting from any use of its research or the information it contains.
This report contains “forward-looking” statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Such statements involve a number of risks and uncertainties such as competition, market demand, and the company’s (and management’s) ability to correctly forecast financial estimates. As a result, the actual results, events, performance or achievements of the financial product may be materially different from those expressed or implied in such statements. Please see the Company’s MD&A “Risk Factors” Section for a more complete discussion of company specific risks for the company discussed in this report. Any opinion or estimate constitutes the preparer’s best judgment as of the date of preparation, and is subject to change without notice. ARC assumes no obligation to maintain or update this report based on subsequent information and events.
ARC is receiving a cash compensation from Rio2 Limited for 12-months of research coverage. This report was disseminated on behalf of Rio2 Limited ARC retains full editorial control over its research content. ARC does not have investment banking relationships and does not expect to receive any investment banking driven income. ARC reports are primarily disseminated electronically and, in some cases, printed form. Electronic reports are simultaneously available to all recipients in any form. This report or any portion hereof may not be copied, reprinted, sold, or redistributed or disclosed by the recipient or any third party, by content scraping or extraction, automated processing, or any other form or means, without the prior written consent of ARC. Any unauthorized use is prohibited. Neither ARC nor any of its respective directors, officers or employees is responsible for guaranteeing the financial success of any investment, or accepts any liability whatsoever for any direct, indirect or consequential damages or losses arising from any use of this report or its contents.
To receive future reports on covered companies please visit https://www.atriumresearch.ca/research or subscribe on our website.
This report has been prepared independently of any issuer of securities mentioned herein and not as agent of any issuer of securities. No ARC personnel have authority whatsoever to make any representations or warranty on behalf of the Company. Any comments or statements made herein are those of ARC.
The information contained herein is not, and under no circumstances is to be construed as, an offer to sell securities described herein, or solicitation of an offer to buy securities described herein, in Canada or any province or territory thereof. Any offer or sale of the securities described herein in Canada will be made only under an exemption from the requirements to file a prospectus with the relevant Canadian securities regulators, if applicable, and only by a dealer properly registered under applicable securities laws or, alternatively, pursuant to an exemption from the dealer registration requirement in the relevant province or territory of Canada in which such offer or sale is made. The information contained herein is under no circumstances to be construed as investment advice in any province or territory of Canada and is not tailored to the needs of the recipient. To the extent that the information contained herein references securities of an issuer incorporated, formed or created under the laws of Canada or a province or territory of Canada, any trades in such securities must be conducted through a dealer registered in Canada. No securities commission or similar regulatory authority in Canada has reviewed or in any way passed judgment upon this research report, the information contained herein or the merits of the securities described herein, and any representation to the contrary is an offence.
The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
