
Author: Atrium Research October 19, 2026
Nicholas Cortellucci, CFA | Equity Research Analyst | [email protected] | 647-391-3314
Luca Perna | Equity Research Associate | [email protected] | 647-969-1027
PLEASE REVIEW THE DISCLOSURES AT THE BOTTOM OF THE PAGE
What you need to know:
-
ROMJ announced a $3.0M private placement with Siwash Rock Investments at $0.45/share, including no warrants or finder’s fees.
-
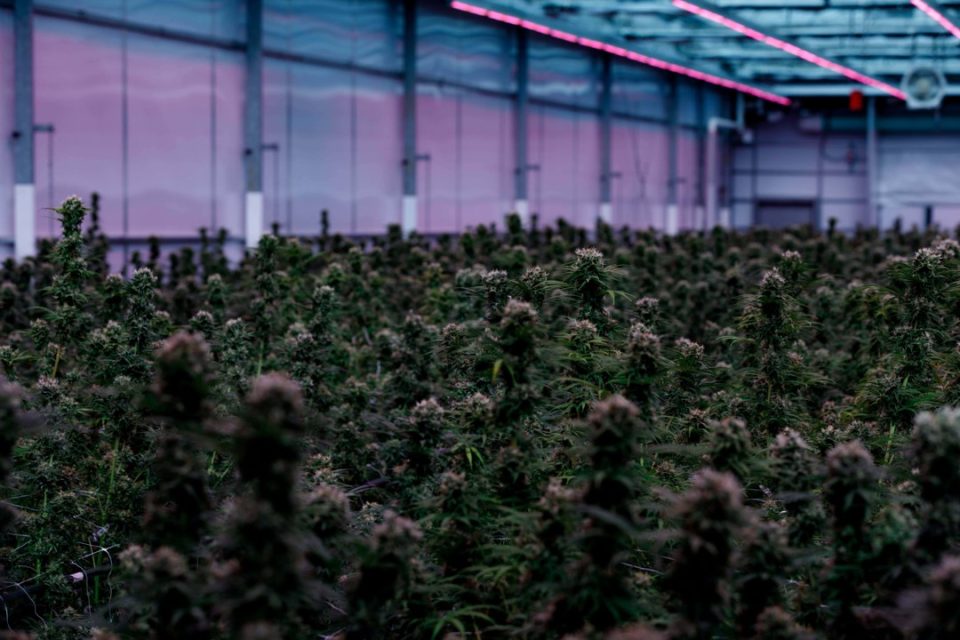
The financing will go toward upgrading lighting solutions at Pacifica, increasing total annual capacity by 29% from 15,500kg to 20,000kg. This will also contribute to lower per-unit costs and increased gross margins.
-
We also provide a preview of Q3 financials which we believe are a key catalyst for the stock.
Yesterday, Rubicon Organics Inc. (ROMJ:TSXV, ROMJF:OTCQX) announced a $3.0M private placement which will go towards upgrading lighting infrastructure at Pacifica. This should result in annual production capacity increasing 40% from 15,500kg to 20,000kg. We also provide a preview of our Q3 financials, which we expect to be a major inflection point for the Company, with the Cascadia ramp progressing. We are maintaining our BUY rating and $1.00/share target price on ROMJ.
Private Placement for Lighting Project Rubicon closed on a strategic non-brokered private placement with Siwash Rock Investments (led by Ted Reid), issuing ~6.67M common shares at $0.45/share for gross proceeds of ~$3.0M. This represents a slight premium to the last close. Proceeds will primarily be used to upgrade cultivation lighting and related infrastructure at the Pacifica facility (“The Lighting Project”), with the remainder allocated to working capital. The upgrades are expected to increase Pacifica’s annual production capacity by 40% to 15,500kg, bringing total Company capacity, including the Cascadia facility, to 20,000kg by June 2027. This accelerates ROMJ’s expansion plans by approximately one year, capturing the winter 2026 season.
Management stated that demand for Rubicon’s premium-quality cannabis has consistently exceeded its supply capacity, and the investment is expected to help address unmet demand by increasing total production capacity by 29%, while also lowering per-unit costs and increasing gross margins. As for our model, we have increased our expectations for 2027, now modelling revenue of $86.5M (previously $83.7M) and adjusted EBITDA of $12.0M (previously $11.6M). The bulk of the benefits from this project will be seen in 2028 (estimates not introduced yet).
Q3 Financials Preview ROMJ will be reporting Q3 financial results around mid-November. This represents an important quarter as Cascadia’s revenue begins to increase and margins are expected to improve. We are expecting the following results (unchanged):
-
Revenue of $20.2M (+29% YoY, +50% on the two-year stack) vs. Capital IQ consensus of $20.0M.
-
Gross margin of 36% compared to 29% in Q2/26 and 34% in Q3/25.
-
Adjusted EBITDA of $1.7M (9% margin, flat YoY) vs. consensus of $2.0M.
Expands UK Portfolio with Full Spectrum Vapes On September 18ᵗʰ, ROMJ announced the launch of 1964 full spectrum vapes in the United Kingdom through its distribution partnership with 4C LABS. The launch builds on 1964’s initial UK entry in April with its Blue Dream and Stinky Pinky flower strains (see our note here), a portfolio that has since expanded to include Apples and Bananas flower. Extending the brand’s premium genetics into vape formats gives UK medical patients additional consumption options beyond flower while broadening 1964’s presence in a fast-growing market, with management citing UK patient numbers expected to grow 40% this year and rising demand for vape products.
To view the complete report, click on the button above.
Analyst Certification
Each authoring analyst of Atrium Research on this report certifies that (i) the recommendations and opinions expressed in this research accurately reflect the authoring analyst’s personal, independent and objective views about any and all of the designated securities discussed (ii) no part of the authoring analyst’s compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views expressed in the research, (iii) to the best of the authoring analyst’s knowledge, she/he is not in receipt of material non-public information about the issuer, (iv) the analyst does not own common shares, options, or warrants in the company under coverage, (v) the analysts adhere to the CFA Institute guidelines for analyst independence, and (vi) this report belongs to the CFA Institute.
Atrium Research Ratings System
BUY: The stock is expected to generate returns of over 20% over the next 24 months.
HOLD: The stock is expected to generate returns of 0-20% over the next 24 months.
SELL: The stock is expected to generate negative returns over the next 24 months.
NOT RATED (N/R): Atrium does not provide research coverage on the respective company.
COVERED COMPANIES: 55
About Atrium Research
Atrium Research provides institutional quality company sponsored research on public equities in North America. Our investment philosophy takes a 3-5 year view on equities currently being overlooked by the market. Our research process emphasizes understanding the key performance metrics for each specific company, trustworthy management teams, and an in-depth valuation analysis. For further information on our team, please visit https://www.atriumresearch.ca/team.
General Information
Atrium Research Corporation (ARC) has created and distributed this report. This report is a general discussion of the merits and risks of a security or securities only, was prepared for general circulation, is not in any way meant to be tailored to the needs and circumstances of any recipient and does not provide investment recommendations specific to individual investors. As such, the securities discussed in this report may not be suitable for all investors and investors must make their own investment decisions based upon their specific investment objectives and financial situation, utilizing their own financial advisors as they deem necessary.
This report is based on information we considered reliable; we have not been provided with any material non-public information by the company (or companies) discussed in this report. We do not represent that this report is accurate or complete and it should not be relied upon as such; further any information in this report is subject to change without any formal or type of notice provided. Investors should consider this report as only one factor in their investment decisions; this report is not intended as a replacement for investor’s independent judgment.
ARC is not a CIRO registered dealer and does not offer investment-banking services to its clients. ARC (and its employees) do not own, trade or have a beneficial interest in the securities of the companies we provide research services for and does not serve as an officer or Director of the companies discussed in this report. ARC does not make a market in any securities. This report is not disseminated in connection with any distribution of securities and is not an offer to sell or the solicitation of an offer to buy any security in any jurisdiction where such an offer or solicitation would be illegal.
ARC does not make any warranties, expressed or implied, as to the results to be obtained from using this information and makes no express of implied warranties for particular use. Anyone using this report assumes full responsibility for whatever results they obtain. This report does not constitute a personal recommendation or take into account any financial or investment objectives, portfolio holdings, strategy, financial situations or needs of individuals. This report has not been prepared for any particular individual or institution. As such, any advice or recommendation in this report may not be suitable for a particular recipient. ARC assumes recipients of this report are capable of evaluating the information contained herein and of exercising independent judgment. A recipient of this report should not make any investment decision without first considering whether any advice or recommendation in this report is suitable for the recipient based on the recipient’s particular circumstances and, if appropriate or otherwise needed, seeking professional advice, including tax advice. ARC does not perform any suitability or other analysis to check whether an investment decision made by the recipient based on this report is consistent with a recipient’s investment objectives, portfolio holdings, strategy, financial situation, or needs. Past performance is not an indication or guarantee of future results, future returns are not guaranteed, and loss of original capital may occur. By providing this report, ARC does not accept any authority, discretion, or control over the management of the recipient’s assets. Any action taken by the recipient of this report, based on the information in the report, is at the recipient’s sole judgment and risk. The recipient must perform his or her own independent review of any prospective investment. Neither ARC nor any person employed by ARC accepts any liability whatsoever for any direct or indirect loss resulting from any use of its research or the information it contains.
This report contains “forward-looking” statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Such statements involve a number of risks and uncertainties such as competition, market demand, and the company’s (and management’s) ability to correctly forecast financial estimates. As a result, the actual results, events, performance or achievements of the financial product may be materially different from those expressed or implied in such statements. Please see the Company’s MD&A “Risk Factors” Section for a more complete discussion of company specific risks for the company discussed in this report. Any opinion or estimate constitutes the preparer’s best judgment as of the date of preparation, and is subject to change without notice. ARC assumes no obligation to maintain or update this report based on subsequent information and events.
ARC is receiving a cash compensation from Rubicon Organics Inc. for 12-months of research coverage. This report was disseminated on behalf of Rubicon Organics Inc. ARC retains full editorial control over its research content. ARC does not have investment banking relationships and does not expect to receive any investment banking driven income. ARC reports are primarily disseminated electronically and, in some cases, printed form. Electronic reports are simultaneously available to all recipients in any form. This report or any portion hereof may not be copied, reprinted, sold, or redistributed or disclosed by the recipient or any third party, by content scraping or extraction, automated processing, or any other form or means, without the prior written consent of ARC. Any unauthorized use is prohibited. Neither ARC nor any of its respective directors, officers or employees is responsible for guaranteeing the financial success of any investment, or accepts any liability whatsoever for any direct, indirect or consequential damages or losses arising from any use of this report or its contents.
To receive future reports on covered companies please visit https://www.atriumresearch.ca/research or subscribe on our website.
This report has been prepared independently of any issuer of securities mentioned herein and not as agent of any issuer of securities. No ARC personnel have authority whatsoever to make any representations or warranty on behalf of the Company. Any comments or statements made herein are those of ARC.
The information contained herein is not, and under no circumstances is to be construed as, an offer to sell securities described herein, or solicitation of an offer to buy securities described herein, in Canada or any province or territory thereof. Any offer or sale of the securities described herein in Canada will be made only under an exemption from the requirements to file a prospectus with the relevant Canadian securities regulators, if applicable, and only by a dealer properly registered under applicable securities laws or, alternatively, pursuant to an exemption from the dealer registration requirement in the relevant province or territory of Canada in which such offer or sale is made. The information contained herein is under no circumstances to be construed as investment advice in any province or territory of Canada and is not tailored to the needs of the recipient. To the extent that the information contained herein references securities of an issuer incorporated, formed or created under the laws of Canada or a province or territory of Canada, any trades in such securities must be conducted through a dealer registered in Canada. No securities commission or similar regulatory authority in Canada has reviewed or in any way passed judgment upon this research report, the information contained herein or the merits of the securities described herein, and any representation to the contrary is an offence.
The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
