
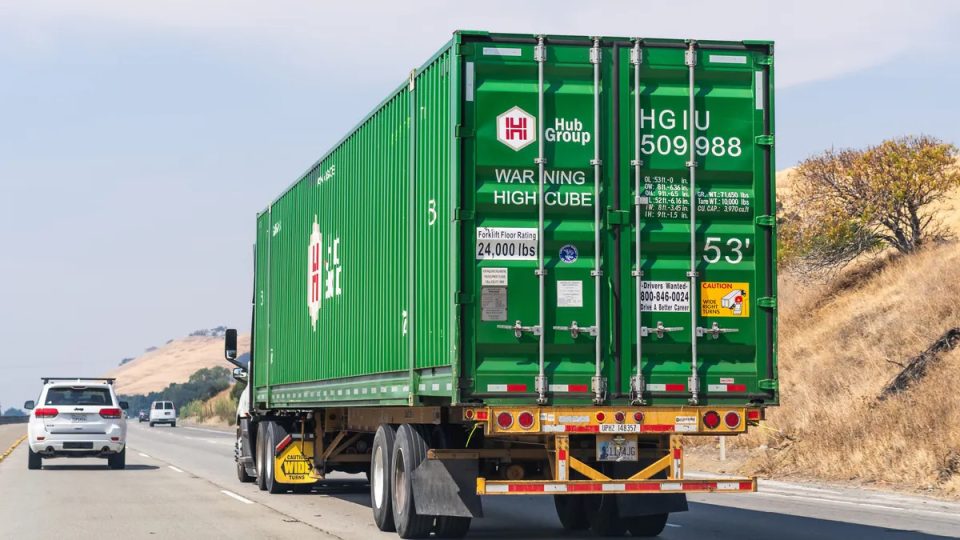
Almost every product on a store shelf has a travel history that the shopper never sees. A container leaves a port, rides a train across several states, moves to a truck for the last stretch, and then waits in a warehouse until a retailer needs it. Few manufacturers or retailers want to run all of that themselves, so they hire specialists. These firms are known as third-party logistics providers, and their job is to plan, buy and manage freight movement on behalf of customers.
The business comes in several forms. Intermodal service combines rail for the long haul with trucks at either end, which usually costs less than an all-highway trip. Brokerage matches a customer’s load with an independent trucking company. Managed transportation goes further, with the provider taking over a customer’s entire shipping operation, from choosing carriers to auditing freight bills. Many providers also offer warehousing, order fulfillment, and final mile delivery of bulky items such as appliances and furniture.
Technology is what ties these pieces together. Providers run transportation management software that compares routes and prices, tracks shipments in real time, and flags delays before they become missed deliveries. Customers increasingly expect a single screen showing where every shipment sits. The scale is considerable. Consultancy Armstrong & Associates estimates that domestic transportation management alone produced about $128.3 billion in gross revenue for U.S. providers in 2025, up 4.5% from a year earlier, as the market rebalanced following the unusually tight conditions of 2021 and 2022.
One feature of the model matters for what follows. Much of a logistics provider’s revenue passes straight through to the railroads and trucking companies that actually move the freight. That expense, called purchased transportation, is by far the largest line on the income statement, and it involves thousands of invoices that often arrive after a shipment is complete. Estimating those bills correctly each quarter is essential, because a small percentage error can translate into tens of millions of dollars.
That is where Hub Group, Inc. (NASDAQ: HUBG) found itself this year. The Oak Brook, Illinois company, which has roughly 6,000 employees and drivers, said in February that it had understated purchased transportation costs and accounts payable during the first nine months of 2025, an error tied to $77 million. Its shares fell about 18% the next day. The review later widened to include 2023 and 2024, and the company has still not filed its 2025 annual report or its reports for the first two quarters of 2026.
Those missing reports explain the delisting question. Hub Group is not choosing to leave Nasdaq. The exchange requires listed companies to file financial reports on time, and it gave the company until September 14 to catch up. When that date passed, Nasdaq staff issued a delisting determination on September 16. Hub Group appealed, and the delisting is on hold until a hearing set for October 27, where the company plans to argue for more time. It expects to finish the restatement and file the overdue reports in the fourth quarter. Lenders have also extended their deadline for the financial statements to November 30.
Against that backdrop came a boardroom overhaul. On October 1, members of the Yeager family and related trusts, who hold a majority of the voting power, used a written consent to remove directors Michael Flannery, Peter McNitt and Gary Yablon without cause. They appointed Gregory D. Bunch, Thomas P. Fitzgerald, Thaddeus J. Malik and Thomas M. White, and adopted new bylaws. Three more directors, Mary H. Boosalis, Jenell Ross and Martin P. Slark, then resigned. The board now has seven members. White is a former Hub Group finance chief, and Malik and Fitzgerald are veteran corporate lawyers.
The company says the changes do not affect management or daily operations, and that it intends to keep a majority of independent directors. David Yeager, who returned as chief executive in September, remains chairman. What the release does not explain is why the directors were removed. For shareholders, the practical question is whether a board reshaped by the founding family can deliver audited numbers quickly enough to satisfy the Nasdaq panel. The hearing on October 27 will offer the first real answer.
