
Author: Couloir Research Team November 14, 2026
PLEASE REVIEW THE DISCLAIMER ON PAGE 8
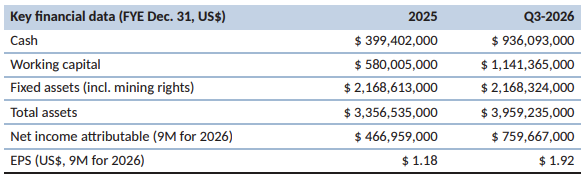
Since our October 2025 update, which placed China Gold Under Review following the contempt ruling and worldwide freezing order against its parent, China National Gold Group Hong Kong (CNGHK), the Company has delivered the strongest financial results in its history. FY2025 net profit reached US$472.3 million (FY2024: US$65.3 million) on 73% revenue growth, and net profit for the first nine months of 2026 has already reached US$766.3 million. The shares responded, peaking at a weekly close of C$47.80 in early September, before retreating to C$29.58 at the close on November 13, the day after the Q3 release.
Two things have changed since the peak. First, the commodity backdrop has turned: gold posted its worst October since 2008, briefly rebounded above US$4,100/oz after the US midterm election results, and was back at US$3,898/oz (London fix) on November 13, ~17% below its H1 2026 average of ~US$4,690/oz. Copper has also eased to ~US$6.17/lb (LME cash, November 13). Second, the governance questions we raised a year ago remain unanswered. The Hong Kong freezing order over CNGHK’s China Gold shares has not, to our knowledge, been discharged, CNGHK lost its application to set aside the arbitration awards in February 2026, and China Gold has still not addressed the matter in its disclosure.
We are removing the Under Review designation. The Q3 results were better than we had modelled, and after a 38% pullback from the September high the shares now trade broadly in line with peers on consensus estimates. Our own 2027 estimates, at a gold price below consensus, still point to modest downside, and the parent overhang remains unresolved. Balancing these factors, we set a fair value of C$26.84 per share and a HOLD rating.
Investment Highlights
- China Gold International Resources Corp. Ltd. (TSX: CGG) (“China Gold”, or “Company”) is a polymetallic miner with two producing assets in the Greater China Region — the CSH gold mine and the Jiama copper-gold polymetallic mine. The Company has delivered a return of approximately 1,770% since our initiation report on August 27, 2020, and 32% since our October 22, 2025 update.
- Strong Q3 despite the CSH suspension. Q3 2026 revenue rose 32% YoY to US$454.0 million and net profit rose 79% to US$254.1 million, even with the CSH open pit idle for the whole quarter. Nine-month net profit of US$766.3 million is more than double last year’s, and net cash rose to ~US$828 million at September 30.
- The metal tailwind is fading. Gold was back at US$3,898/oz on November 13, roughly 30% below its January peak and ~17% below its H1 average. China Gold shares fell ~6% after the Q3 release and are down ~38% from their September high. CSH mining resumed in early October.
- Parent overhang unresolved. A Hong Kong freezing order still covers 34.1 million China Gold shares (8.6%) held by CNGHK, whose bid to set aside the Gerald arbitration awards failed in February. China Gold has made no disclosure, while its parent group remains its sole customer and a key deposit bank.
- Remove Under Review; change rating to HOLD. On consensus estimates, China Gold now trades in line with peers. Blending a valuation on our more conservative estimates with a like-for-like consensus valuation, our fair value is C$26.84 per share, 9% below the current price.
To view the complete report, click on the button above.
This report has been prepared by an analyst on contract with or employed by Couloir Capital Ltd. The analyst certifies that the views expressed in this report, which include the rating assigned to the issuer’s shares as well as the analytical substance and tone of the report, accurately reflect his or her personal views about the subject securities and the issuer. No part of his / her compensation was, is, or will be directly or indirectly related to the specific recommendations.
Couloir Capital, its affiliates, and their respective officers, directors, representatives, researchers, and members of their families may hold positions in the companies mentioned in this document and may buy and/or sell their securities. Additionally, Couloir Capital may have provided, in the past and may provide, in the future, certain advisory or corporate finance services and receive financial and other incentives from issuers as consideration for the provision of such services.
Couloir Capital has prepared this document for general information purposes only. This document should not be considered a solicitation to purchase or sell securities or a recommendation to buy or sell securities. The information provided has been derived from sources believed to be accurate, but cannot be guaranteed. This document does not consider the particular investment objectives, financial situations, or needs of individual recipients and other issues (e.g., prohibitions to investments due to law, jurisdiction issues, etc.) that may exist for certain persons. Recipients should rely on their own investigations and take their own professional advice before making an investment. Couloir Capital will not treat recipients of this document as clients by virtue of having viewed this document.
Company-specific disclosures, if any, are below:
1. In the last 24 months, Couloir Capital Ltd. has been retained by the subject issuer under a service agreement that includes analyst research coverage.
2. The views of the Analyst are personal.
3. No part of the Analyst’s compensation was directly or indirectly related to the specific ratings as used by the research Analyst in the Reports.
4. The Analyst does not maintain a financial interest in the securities or options of the Company.
5. The principal of Couloir Capital maintains a financial interest in the securities or options of the Company through an affiliated hedge fund entity.
6. The information contained in the Reports is based upon publicly available information that the Analyst believes to be correct but has not independently verified with respect to truth or correctness.
Investment Ratings -Recommendations
Each company within an analyst’s universe, or group of companies covered, is assigned:
1. A recommendation or rating, usually BUY, HOLD, or SELL;
2. A 12-month target price, which represents an analyst’s current assessment of a company’s
potential stock price over the next year; and
3. An overall risk rating which represents an analyst’s assessment of the company’s overall investment risk.
These ratings are more fully explained below. Before acting on a recommendation, we caution you to confer with your investment advisor to determine the suitability of our recommendation for your specific investment objectives, risk tolerance, and investment time horizon.
Couloir Capital’s recommendation categories include the following:
Buy
The analyst believes that the security will outperform other companies in their sector on a risk-adjusted basis or for the reasons stated in the research report the analyst believes that the security is deserving of a (continued) BUY rating.
Hold
The analyst believes that the security is expected to perform in line with other companies in their sector on a risk-adjusted basis or for the reasons stated in the research report the analyst believes that the security is deserving of a (continued) HOLD rating.
Sell
Investors are advised to sell the security or hold alternative securities within the sector. Stocks in this category are expected to under-perform other companies on a risk-adjusted basis or for the reasons stated in the research report the analyst believes that the security is deserving of a (continued) SELL rating.
Tender
The analyst is recommending that investors tender to a specific offering for the company’s stock.
Research Comment
An analyst comment about an issuer event that does not include a rating.
Coverage Dropped
Couloir Capital will no longer cover the issuer. Couloir Capital will provide notice to clients whenever coverage of an issuer is discontinued. Following termination of coverage, we recommend clients seek advice from their respective Investment Advisor.
Under Review
Placing a stock Under Review does not revise the current rating or recommendation of the analyst. A stock will be placed Under Review when the relevant company has a significant material event with further information pending or to be announced. An analyst will place a stock Under Review while he/she awaits enough information to re-evaluate the company’s financial situation.
The above ratings are determined by the analyst at the time of publication. On occasion, total returns
may fall outside of the ranges due to market price movements and/or short-term volatility.
Overall Risk Rating
Very High Risk: Venture-type companies or more established micro, small, mid or large-cap companies whose risk profile parameters and/or lack of liquidity warrant such a designation. These companies are only appropriate for investors who have a very high tolerance for risk and volatility and who can incur a temporary or permanent loss of a very significant portion of their investment capital.
High Risk: Typically, micro or small-cap companies which have an above-average investment risk relative to more established or mid to large-cap companies. These companies will generally not form part of the broad senior stock market indices and often will have less liquidity than more established mid and large-cap companies. These companies are only appropriate for investors who have a high tolerance for risk and volatility and who can incur a temporary or permanent loss of a significant portion of their investment capital.
Medium-High Risk: Typically, mid to large-cap companies have a medium to high investment risk. These companies will often form part of the broader senior stock market indices or sector-specific indices. These companies are only appropriate for investors who have a medium to high tolerance for risk and volatility and who are prepared to accept general stock market risk including the risk of a temporary or permanent loss of some of their investment capital
Moderate Risk: Large to very large cap companies with established earnings who have a track record of lower volatility when compared against the broad senior stock market indices. These companies are only appropriate for investors who have a medium tolerance for risk and volatility and who are prepared to accept general stock market risk including the risk of a temporary or permanent loss of some of their investment capital.
